13 min read • Published 4 June 2026 • Last updated 27 September 2026
Most upcoming launch pages are a list of names and a registration form.
That is not much help when you are trying to decide whether to move this year or next.
What does help is the one number that already exists before any show flat opens.
The price the developer paid for the land.
It is public. It is fixed. And it sets the floor under everything you will later be quoted.
So this page starts there, and works forward.
1. What Is Launching in Singapore, and When?
Sixteen Singapore condominium and executive condominium launches are scheduled between September 2026 and the end of the first quarter of 2027, adding about 7,760 homes. The next is Lucerne Grand in Jurong on 11 September 2026. The largest is Thomson Reserve, with 1,268 units in District 20, previewing 3 to 10 October 2026.
Key takeaways
- 16 launches are scheduled from 11 September 2026 to the end of March 2027, totalling roughly 7,760 homes. Several unit counts are still estimates.
- The land under them was bought for between $692 and $1,865 per square foot of buildable space. That spread of 170% is why one launch opens near $1,800 psf and another near $3,800 in the same year.
- Five of the 16 are executive condominiums, and all five were tendered under the old five-year MOP rules. No future EC will be.
- Across the wider pipeline, 29 projects have a target preview window running through Q4 2027, and six more awarded sites have no date yet.
- Every launch price on this page is an estimate built from land cost. No developer has published a price list for any of these projects.
The table below covers the launches with a target window between now and the end of March 2027.
Land rates are the winning tender or collective sale price, quoted per square foot of buildable space. Indicative launch prices are estimates from the PropertyInsider.sg pricing model, not developer figures.
| Project | Target preview | District | Type | Est. units | Land $psf ppr | Indicative launch psf (est.) | Developer |
|---|---|---|---|---|---|---|---|
| Lucerne Grand | 11 Sep 2026 | D22 · OCR | Condo | 570 | $1,132 | $2,450–$2,900 | CDL |
| Amberwood at Holland | Sep/Oct 2026 | D10 · CCR | Condo | 212 | $1,432 | $3,000–$3,500 | Sim Lian Group |
| The Serra Residences | Sep/Oct 2026 | D11 · CCR | Condo | 133 | Not disclosed | $3,000–$3,500 | Far East Organization |
| Belgravia Ace | Sep/Oct 2026 | D28 · OCR | Condo | 104 | Not disclosed | Not yet estimated | Tong Eng Group |
| Thomson Reserve | 3–10 Oct 2026 | D20 · RCR | Condo | 1,268 | $1,178 | $2,450–$2,700 | UOL / CapitaLand / Singapore Land Group |
| Wynwood Grand (EC) | Q4 2026 | D25 · OCR | EC | 420 | $782 | $1,800–$2,100 | CDL |
| The Island Residence | Q4 2026 | D04 · CCR | Condo | 84 | Not disclosed | $2,800–$3,300 | Keppel |
| Chuan Grove GLS | Q1 2027 | D19 · OCR | Condo | 1,055 | $1,355 | $2,500–$2,700 | Sing Holdings / Sunway |
| Chencharu Close GLS | Q1 2027 | D27 · OCR | Mixed-use | 864 | $980 | $2,350–$2,700 | Evia / Gamuda Land / Ho Lee Group |
| Telok Blangah Road GLS | Q1 2027 | D04 · RCR | Condo | 745 | $1,326 | $2,450–$3,100 | Kingsford Development |
| Upper Thomson (Parcel A) GLS | Q1 2027 | D26 · OCR | Condo | 595 | $1,062 | $2,350–$2,600 | Wee Hur Holdings |
| Dorset Road GLS | Q1 2027 | D08 · RCR | Condo | 428 | $1,338 | $2,500–$3,000 | UOL / Singapore Land Group / Kheng Leong |
| Bedok Rise GLS | Q1 2027 | D16 · OCR | Condo | 380 | $1,330 | $2,450–$2,600 | Allgreen Properties |
| Bukit Timah Road GLS | Q1 2027 | D11 · CCR | Condo | 340 | $1,820 | $3,500–$3,800 | HH Investment |
| Solano Grand (Senja Close EC) | Q1 2027 | D23 · OCR | EC | 295 | $771 | $1,800–$2,200 | CDL |
| Sembawang Road (EC) | Q1 2027 | D27 · OCR | EC | 265 | $692 | $1,800–$2,100 | JBE Holdings |
Three projects that appeared on earlier versions of this page have been removed: Hudson Place Residences, Dunearn House and Lentor Gardens Residences.
The first two could not be reconciled against the tender record. The third has already previewed, so it no longer belongs on a forward calendar. My review of Lentor Gardens Residences in District 26 stays published for anyone still weighing it.
2. Where These Numbers Come From
A launch calendar is only worth as much as its sourcing, so here is the whole chain.
Land rates, tender dates and winning prices come from published URA and HDB tender results. Collective sale figures are reported transaction prices. Unit counts come from tender conditions or developer announcements, and stay marked as estimates until a developer confirms the mix.
The launch price ranges are model output, not forecasts of any particular price list. They are produced on PropertyInsider.sg's upcoming launch calendar, the research platform I founded, and rebuilt each time a tender is awarded or a preview date is confirmed.
I run that platform, so treat this page as the advisory read on the data rather than an independent check of it. Where the two disagree, the platform is the live version and this page is the slower one.
Four terms this page leans on
- psf ppr — dollars per square foot of floor space the developer is allowed to build. Quoting land this way lets you compare a small tall site against a large low one.
- Breakeven — everything the project costs the developer, divided by that same buildable space. Below this price, they lose money.
- Preview — the weekend the show flat opens and prices are released. Until a developer confirms it, every date here is an estimate.
- EC — executive condominium. Cheaper than a private condo, but with HDB conditions attached: an income ceiling, a minimum period living in it, and a levy on resale.
3. Why Land Cost Is the Earliest Price Signal
A launch price is decided long before a show flat opens.
Two to three years earlier, a developer commits to a land cost. Construction, borrowing, marketing and profit all stack on top of it. So watching land tenders is watching launch prices form, years before they exist.
Across the 71 pipeline sites with a published cost breakdown, land accounts for about 55% of what a project costs, ranging from 47% to 65% depending on the site.
That is why breakeven typically lands around 1.8 times the land rate. Add a developer margin of 15% to 30%, and you have a launch range.
Thomson Reserve shows the whole chain in one project.
A rougher cross-check also works: launch price at about 2.1 times the land rate. On Thomson Reserve that gives $2,474, which sits inside the range above.
But the multiple is not constant. On sites under $900 psf ppr it runs closer to 2.5 times. Above $1,600 it falls to roughly 1.9. Concrete, consultants and bank interest cost much the same whichever site they are spent on, so they shrink as a share of the bill when land gets dearer.
What the pipeline paid, by land band
Grouping the awarded sites by what they paid makes the shape of the pipeline visible in a way that a single ranked list does not.
| Land band ($psf ppr) | Sites in the band | Indicative launch range (est.) |
|---|---|---|
| Under $800 — EC land | Sembawang Road $692, Miltonia Close $732, Solano Grand $771, Wynwood Grand $782, Woodlands Drive 17 $794 | $1,800–$2,200 psf |
| $950 to $1,100 | Dairy Farm Walk $962, Chencharu Close $980, Upper Thomson Parcel A $1,062 | $2,350–$2,700 psf |
| $1,100 to $1,200 | Lucerne Grand $1,132, Thomson Reserve $1,178, Hougang Central $1,179 | $2,450–$2,900 psf |
| $1,250 to $1,500 | Lentor Central Plot 4 $1,278, Bayshore Drive $1,323, Telok Blangah Road $1,326, Bedok Rise $1,330, Dorset Road $1,338, One Chuan Grove $1,355, Kallang Close $1,415, Amberwood at Holland $1,432, Tanjong Rhu Road $1,455, Holland Plain $1,491 | $2,450–$3,300 psf |
| Above $1,500 | Dover Drive $1,556, Dunearn Road Plot 2 $1,625, River Valley Green Parcel C $1,730, Bukit Timah Road $1,820, Peck Hay Road $1,865 | $2,700–$4,200 psf |
One reading trap is worth naming here.
Breakeven is measured per square foot of everything the developer builds. Homes are sold per square foot of the area inside your own unit, which is smaller, because lift lobbies, corridors and plant rooms come out of it.
So a project selling 20% above its breakeven rate is not earning anything like a 20% profit. Part of that gap is simply a change in what is being measured.
For how a single tender result feeds through to a specific project, see my walkthrough of the current Government Land Sales pipeline and the GLS tender analysis library.
4. Which Launches Are Closest?
Four projects preview before the end of 2026. These are the ones worth a decision now rather than a bookmark.
Lucerne Grand, 11 September 2026
570 units by CDL at Lakeside Drive in District 22, two minutes on foot from Lakeside MRT on the East-West Line. Land cost $1,132 psf ppr.
Four MOE primary schools sit within a straight-line kilometre. In the 2026 Primary One exercise, Rulang and Shuqun both balloted at Phase 2C even among citizens living inside that ring, which is worth knowing before you treat proximity as access.
My full review of Lucerne Grand works through the cost stack behind its price estimate, the school ballot odds and what Jurong Lake District is actually building.
Thomson Reserve, 3 to 10 October 2026
1,268 units on Bright Hill Drive in District 20, by UOL Group, Singapore Land Group and CapitaLand Development. It is the largest launch in the pipeline.
The land was bought in October 2024 at $1,178 psf ppr. That is 8% to 55% below every comparable central site sold since, which is the single most interesting fact about this project.
Upper Thomson MRT is a four-minute walk. Ai Tong School is within a kilometre. District 20's matched resale record shows 3,629 of 3,822 exits made money, or 95.0%.
Scale cuts both ways. 1,268 units means a large number of homes competing for the same tenants and the same resale buyers at completion.
My Thomson Reserve review works through the pricing, the unit mix and the risks a show flat visit will not surface, and the Thomson Reserve gallery holds the developer perspectives and site plan.
Amberwood at Holland and The Serra Residences, September to October 2026
Two small prime-district launches in the same window. Amberwood at Holland is 212 units on Holland Link in District 10, on land Sim Lian took at $1,432 psf ppr, paying 22.2% above the next bid. The Serra Residences is 133 units in District 11 by Far East Organization.
A 22.2% winning margin is not a market consensus. It is one developer wanting one site more than anyone else did. That is a different thing to buy into, and my Amberwood at Holland review sets out the price and unit mix in detail.
Wynwood Grand and The Island Residence, Q4 2026
Wynwood Grand is CDL's 420-unit executive condominium at Woodlands Drive 17, on land that cost a record-low $782 psf ppr. It sits two MRT stops from the Johor rail link terminus.
The Island Residence is 84 units in District 04 by Keppel. Small, prime, and covered in my review of The Island Residence.
5. The EC Pipeline, and Why the Tender Date Matters
Five executive condominium sites sit in the pipeline. All five are the last of their kind.
On 8 May 2026, the Ministry of National Development announced the biggest revision to the EC framework in over a decade. It applies to EC sites whose land tender closes on or after that date.
- The minimum occupation period doubles from five years to ten
- Full privatisation moves from ten years after completion to fifteen
- The Deferred Payment Scheme is removed
- First-timer allocation rises from 70% of units to 90%, with the priority window extended from one month to two years
Senja Close, Sembawang Road, Miltonia Close and the two Woodlands Drive 17 parcels all closed their tenders before 8 May 2026.
So they keep the five-year MOP. Nothing tendered after them will.
The income ceiling moved too. From 24 August 2026 the EC household ceiling rose from $16,000 to $18,000, but only for projects whose land tender closes on or after that date. The five sites above therefore sit under the $16,000 ceiling.
Two forces, pulling opposite ways. A higher ceiling widens the buyer pool for future ECs. A doubled holding period narrows what those buyers can do with them.
For a household that qualifies under $16,000, five years of MOP against ten is a real difference in flexibility, not a marketing line.
But a shorter holding rule is not the same thing as a better buy. It is worth something only if the launch price, the location, the layout and the competing supply also work.
The full rule set, including the two-date test that decides which generation of EC rules applies to you, is in my analysis of the 2026 HDB and EC income ceiling changes.
6. Which Launches Suit HDB Upgraders?
For a household crossing its minimum occupation period, three parts of this pipeline deserve attention before the rest.
The five remaining ECs, if you qualify. Sembawang Road at $692 psf ppr and Solano Grand at $771 are the cheapest land in the entire pipeline. EC land runs roughly 40% below comparable private suburban land, because HDB caps who is allowed to buy the homes. That gap is structural, not a bargain, but it is real money at entry.
The two integrated sites, if you do not. Chencharu Close at $980 psf ppr is the first private site in a new 70-hectare town of about 10,000 homes, with a bus interchange, hawker centre and shops required to be built into it. Hougang Central at $1,179 sits directly above an MRT station that becomes a two-line interchange in 2030 when the Cross Island Line opens.
Read those two in full in my Chencharu Close GLS guide for District 27 and my Hougang Central integrated development guide.
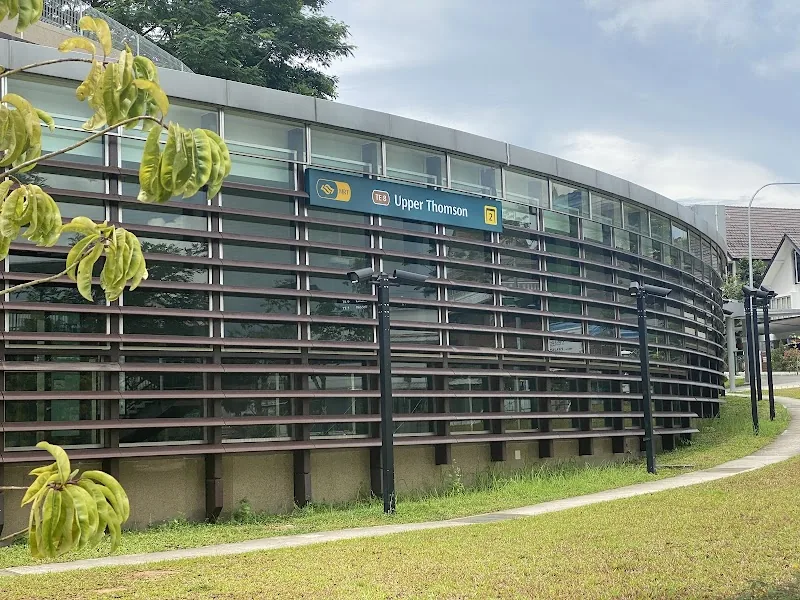
Upper Thomson Parcel A, with one honest catch. 595 units at Springleaf with the MRT entrance built into the block, at $1,062 psf ppr. There is no primary school within a kilometre. For a family balloting for Primary One, that is close to disqualifying.
Before any of this, the sequencing question matters more than the project. Selling first and buying first carry different risks, and the ABSD outlay is the hinge. My asset progression guides work through how one property funds the next, with two case studies showing the full arithmetic.
7. Which Launches Suit Investors?
Investors in 2026 are buying into higher ABSD rates and a visible supply schedule. The old approach of buying early and flipping before completion does not survive either.
What is left is asking where the tenant pool is deep and where the exit audience is wide.
On that test, the city fringe reads better than the suburbs right now. Telok Blangah Road at $1,326 psf ppr is the first private launch on the old Keppel Club land, in an area that has not seen a state land release in 35 years. Dorset Road at $1,338 sits in District 08, close enough to the city for a short commute to be the selling point.
Bedok Rise is worth watching for a different reason. Ten developers bid for it in November 2025 and the top two were $6 apart. A 0.4% winning margin means ten independent teams did their sums and landed in the same place. That makes $1,330 psf ppr a genuine market consensus rather than one company's conviction.
A tight tender tells you what the market thinks. A wide one tells you what one company thinks. Both are useful, and they are not the same signal.
One caution on yield. Every estimate on this page is a price estimate, not a rental forecast. Rents at completion depend on how much competing supply completes in the same window, which is knowable from this pipeline and worth checking project by project.
If you are weighing a launch against something already built, my comparison of new launch and resale condos sets out what each one actually costs you.
8. Where Are the Launches? OCR, RCR and CCR
The three market segments are shorthand for distance from the city centre. Core Central Region is the prime core. Rest of Central Region is the city fringe. Outside Central Region is everything suburban.
In the September 2026 to March 2027 window, the split runs roughly nine suburban, three city fringe and four prime.
That balance matters less than what it costs to sit in each one.
Suburban land in this pipeline runs from $692 to $1,355 psf ppr. City fringe runs from $1,178 to $1,338. Prime runs from $1,432 to $1,865.
Read those bands side by side and the city fringe looks like the narrow part of the ladder. The step up from a good suburban site to a city fringe one is smaller than the step from city fringe to prime.
Whether that makes the fringe good value depends entirely on what you want the property to do. A family who needs four bedrooms near a specific school is not solving the same problem as someone buying rentability.
My OCR, RCR and CCR comparison sets out which segment suits which buyer without pretending one of them wins outright.
For the estates several of these launches sit in, the neighbourhood guides go deeper: living in Hougang, living in Bedok and living in Woodlands.
9. What Is Further Out: Q2 2027 and Beyond
Thirteen more launches carry a target window between Q2 2027 and Q4 2027.
The suburban and fringe group: Hougang Central at $1,179 psf ppr, Lentor Central Plot 4 at $1,278, Woodlands Drive 17 second parcel at $794, Dairy Farm Walk Plot 3 at $962, Dover Drive at $1,556, Tanjong Rhu Road at $1,455 and Kallang Close at $1,415.
The prime group: Holland Plain Parcel B at $1,491, Dunearn Road Plot 2 at $1,625, River Valley Green Parcel C at $1,730 and Peck Hay Road at $1,865. Miltonia Close, an EC at $732, sits at the other end of the same list.
Bayshore Drive closes the calendar in Q4 2027. It is the only mixed-use plot in the Bayshore master plan, a town centre above a new MRT station, taken by a Frasers-led group at $1,323 psf ppr on 15 July 2026. That was above every analyst forecast tracked at the time. My Bayshore Drive GLS analysis covers the master plan and the pricing implication.
Six further awarded sites have no target date at all: Admiralty Walk (EC), Berlayar Drive, Canberra Drive (EC), Lorong Puntong and Sin Ming Avenue, New Upper Changi Road and Town Hall Link. Either their tender has not closed or the developer has not begun positioning a launch.
Two of those have their own analysis here already: my New Upper Changi Road GLS tender note, and my note on the $1,612 psf ppr Lorong Puntong bid in Bishan.
A recent private treaty sale is also worth flagging, because it shows how misleading a headline land price can be. 8 Thomson Lane sold for $578 million, but its effective land cost is $1,297 psf ppr once the land betterment charge from a hotel-to-residential rezoning is folded back in.
10. What Could Go Wrong With This List
A calendar built from land cost has real limits, and they should be on the page rather than in a footnote.
Every price here is an estimate. No developer has published a price list for any of these projects. Developers price against their own books, their own funding costs and their own read of the weekend queue. The model does not see any of that.
Two to three years pass between tender and launch. Building costs and interest rates move in that window, so the relationship between land price and launch price is not fixed.
Dates move. Every preview window marked as a quarter is an estimate. Developers push launches for reasons that have nothing to do with the buyer.
Q1 2027 is crowded. Nine of the sixteen launches on this page fall in a single quarter. That is good for buyers who are ready and difficult for anyone who wants to see how the first few price before committing.
Fewer bidders has not meant cheaper land. Peck Hay Road went for $1,865 psf ppr in June 2026 with four bidders, not eight. Holland Plain drew a single bid in May 2026 and still cleared $1,491. Bidder counts also fall for a mechanical reason: billion-dollar sites rule most developers out before anyone reads the site plan.
A calendar is a shortlist, not a recommendation. Every project on it still has to pass the same five checks any launch does, and my five-point framework for assessing a new launch sets out what those are.
11. My View on the 2026 Pipeline
Three things stand out to me in this set.
The land-cost ranking and the price ranking do not match, and that is the interesting part. Lucerne Grand sits on cheaper land than Thomson Reserve, $1,132 against $1,178, yet its indicative range runs higher. Location, unit mix and competing supply are doing work the land rate alone cannot show. Anyone using land cost as a single-number ranking is using it wrong.
Thomson Reserve is the clearest case of a land price that has aged well. Bought in October 2024, before the run-up, at a rate 8% to 55% below comparable central sites sold since. That does not guarantee a good launch price, because the developer captures the benefit before the buyer does. But it does mean the project has more room to price competitively than most of its neighbours, if it chooses to.
The EC window is closing, and it is being underweighted. Five sites, all under the old five-year MOP, all under the $16,000 ceiling. For a household that qualifies, this is a genuinely time-limited difference in flexibility. It is also the part of the pipeline where the entry price is lowest by a wide margin.
What would change my mind on all three: a materially weaker economy, or a policy move on stamp duty or loan limits. Neither is in the announced pipeline, and neither needs to announce itself in advance.
What I would not do is treat this list as evidence that prices must rise. A deep pipeline is supply. Supply is the argument against price growth, not for it. The reason prices have held is that land costs are already committed, not that demand is unstoppable.
12. What I Would Do in the Next 90 Days
Pick two or three projects whose dates match when you actually need to move. Read only those. A calendar of twenty-nine is a research tool, not a shortlist.
For each one, ask:
- Does the preview window match when I can realistically commit funds?
- What have similar homes nearby actually resold for in the past year?
- If the estimate and the neighbouring resale price are far apart, why?
- How many competing units complete within twelve months of this one?
- If I am looking at an EC, when did its land tender close?
- What happens to my plan if the preview slips two quarters?
Then get your financing position confirmed before the preview, not during it. Booking day is the wrong time to discover a TDSR problem.
Working out where you sit in this pipeline? Tell me what you own now and when you need to move, and I will come back with the two or three launches that actually fit, and the ones that do not. Get in touch.
13. Published Coverage on This Site
The last column separates projects I have reviewed in full from land sites I am still tracking. Worth checking before you plan a show flat visit.
| Project or topic | District | Status | Coverage |
|---|---|---|---|
| Thomson Reserve | D20 | Previews 3–10 Oct 2026 | Full review, plus gallery |
| Lucerne Grand | D22 | Previews 11 Sep 2026 | Full review |
| Amberwood at Holland | D10 | Previews Sep/Oct 2026 | Full review |
| The Island Residence | D04 | Previews Q4 2026 | Full review |
| Lentor Gardens Residences | D26 | Already previewed | Full review |
| 8 Thomson Lane | D11 | Site acquired Aug 2026 | Land cost analysis |
| Hougang Central GLS | D19 | Previews Q2 2027 | Site analysis |
| Chencharu Close GLS | D27 | Previews Q1 2027 | Site analysis |
| Bayshore Drive GLS | D16 | Previews Q4 2027 | Site analysis |
| New Upper Changi Road GLS | D16 | No launch date yet | Tender note |
| Upcoming GLS sites | Islandwide | Standing reference | Pipeline walkthrough |
The decision guides underneath this page
14. Frequently Asked Questions
How many condo launches are there in Singapore in 2026 and 2027?
Sixteen condominium and executive condominium launches are scheduled between 11 September 2026 and the end of March 2027, adding about 7,760 homes. Across the wider pipeline, 29 projects carry a target preview window running through Q4 2027, and six more awarded sites have no date yet. Every date is a target until the developer confirms it.
Which condo is launching next in Singapore?
Lucerne Grand, a 570-unit CDL project at Lakeside Drive in District 22, previews on 11 September 2026. The next after that is the September to October cluster of Amberwood at Holland, The Serra Residences and Belgravia Ace, followed by Thomson Reserve on 3 to 10 October 2026.
What will new launch condos cost per square foot in 2026?
It depends almost entirely on what the developer paid for the land. Executive condominium sites bought at $692 to $794 per square foot of buildable space point to launch prices around $1,800 to $2,200 psf. Suburban private sites around $1,000 to $1,200 point to roughly $2,350 to $2,900 psf. Prime sites above $1,500 point to $3,000 psf and upwards. These are estimates, not developer prices.
Why does a developer's land cost matter to me as a buyer?
Because it is the largest single input into the price you are eventually quoted, and it is fixed years before the show flat opens. Land is about 55% of what a project costs to build. Add construction, financing, fees and marketing, and breakeven typically lands near 1.8 times the land rate. Add a 15% to 30% developer margin on top of that, and you have a launch range.
Which Executive Condominiums are launching in 2026 and 2027?
Five EC sites are in the pipeline: Sembawang Road, Miltonia Close, Solano Grand at Senja Close, and two parcels at Woodlands Drive 17, one of which is CDL's Wynwood Grand. All five closed their land tenders before 8 May 2026, so all five keep the five-year minimum occupation period and the $16,000 household income ceiling. Sites tendered after that date carry a ten-year MOP.
Is it better to buy a new launch or a resale condo in 2026?
It depends on your timeline and your cash position, not on which is generally better. A resale condo gives you immediate occupation or rental income and a price you can verify against recent transactions. A new launch gives you a progressive payment schedule and a longer runway, but you are buying an estimate of what the finished home will be worth. For a household that needs to move within a year, resale usually wins on certainty alone.
Should I wait for the 2027 launches instead?
Waiting is a position, not a neutral choice. The 2027 sites were bought at higher land rates on average than the 2026 ones, so on current evidence they are more likely to price higher rather than lower. That said, if none of the sixteen launches in this window fits your budget, your location or your family's needs, waiting is the right answer. Fit should decide it, not timing.
Where can I check the latest launch dates and land costs?
The live versions of both datasets sit on PropertyInsider.sg, the research platform I founded. The upcoming launch calendar carries all 29 scheduled projects in date order, and the land cost tracker carries the awarded rate, estimated breakeven, bidder count and winning margin for every site. This page is updated less often than they are, so where the two disagree, the tracker is the current one.
15. My Thoughts
A launch calendar looks like a list of opportunities. It is really a list of commitments other people have already made.
Thirty developers have put their money down. Those cheques cannot be un-written. That is why land cost is the honest starting point, and why a page of estimates built on it beats a page of names and a registration form.
But none of it tells you what to do.
The pipeline does not know when your minimum occupation period ends, how much of your sale proceeds are locked in CPF, or whether your household needs to be inside a specific school's kilometre ring.
Those facts decide the answer. The calendar only decides which two or three projects are worth the afternoon.
Buy the fit. Use the pipeline to find it.
Disclaimer
Please note that the property names used on this website are based on road names from Government Land Sales (GLS) sites or en bloc sales, and may not reflect the official names of the developments. These provisional names are provided for reference only and may differ from the final official names.
All calculations, figures, prices, and costs displayed on this website are for illustrative purposes only and do not represent the actual or final selling prices of the developments.
Disclosure: PropertyInsider.sg is a research platform founded and operated by Jamus Lee. Pages on this site cite its published datasets, and it is not an independent third-party source.
We are committed to accuracy and transparency; however, the information provided should not be regarded as an offer, statement, representation, or guarantee. While we strive to ensure the information is correct, it may not always be complete, up to date, or free from errors. Users are strongly encouraged to exercise due diligence and verify details through direct inquiries. Our agents and this website shall not be held liable for any decisions or actions taken based on the information provided here.