17 min read • Figures current as at 27 August 2026
1. What Exactly Are You Buying?
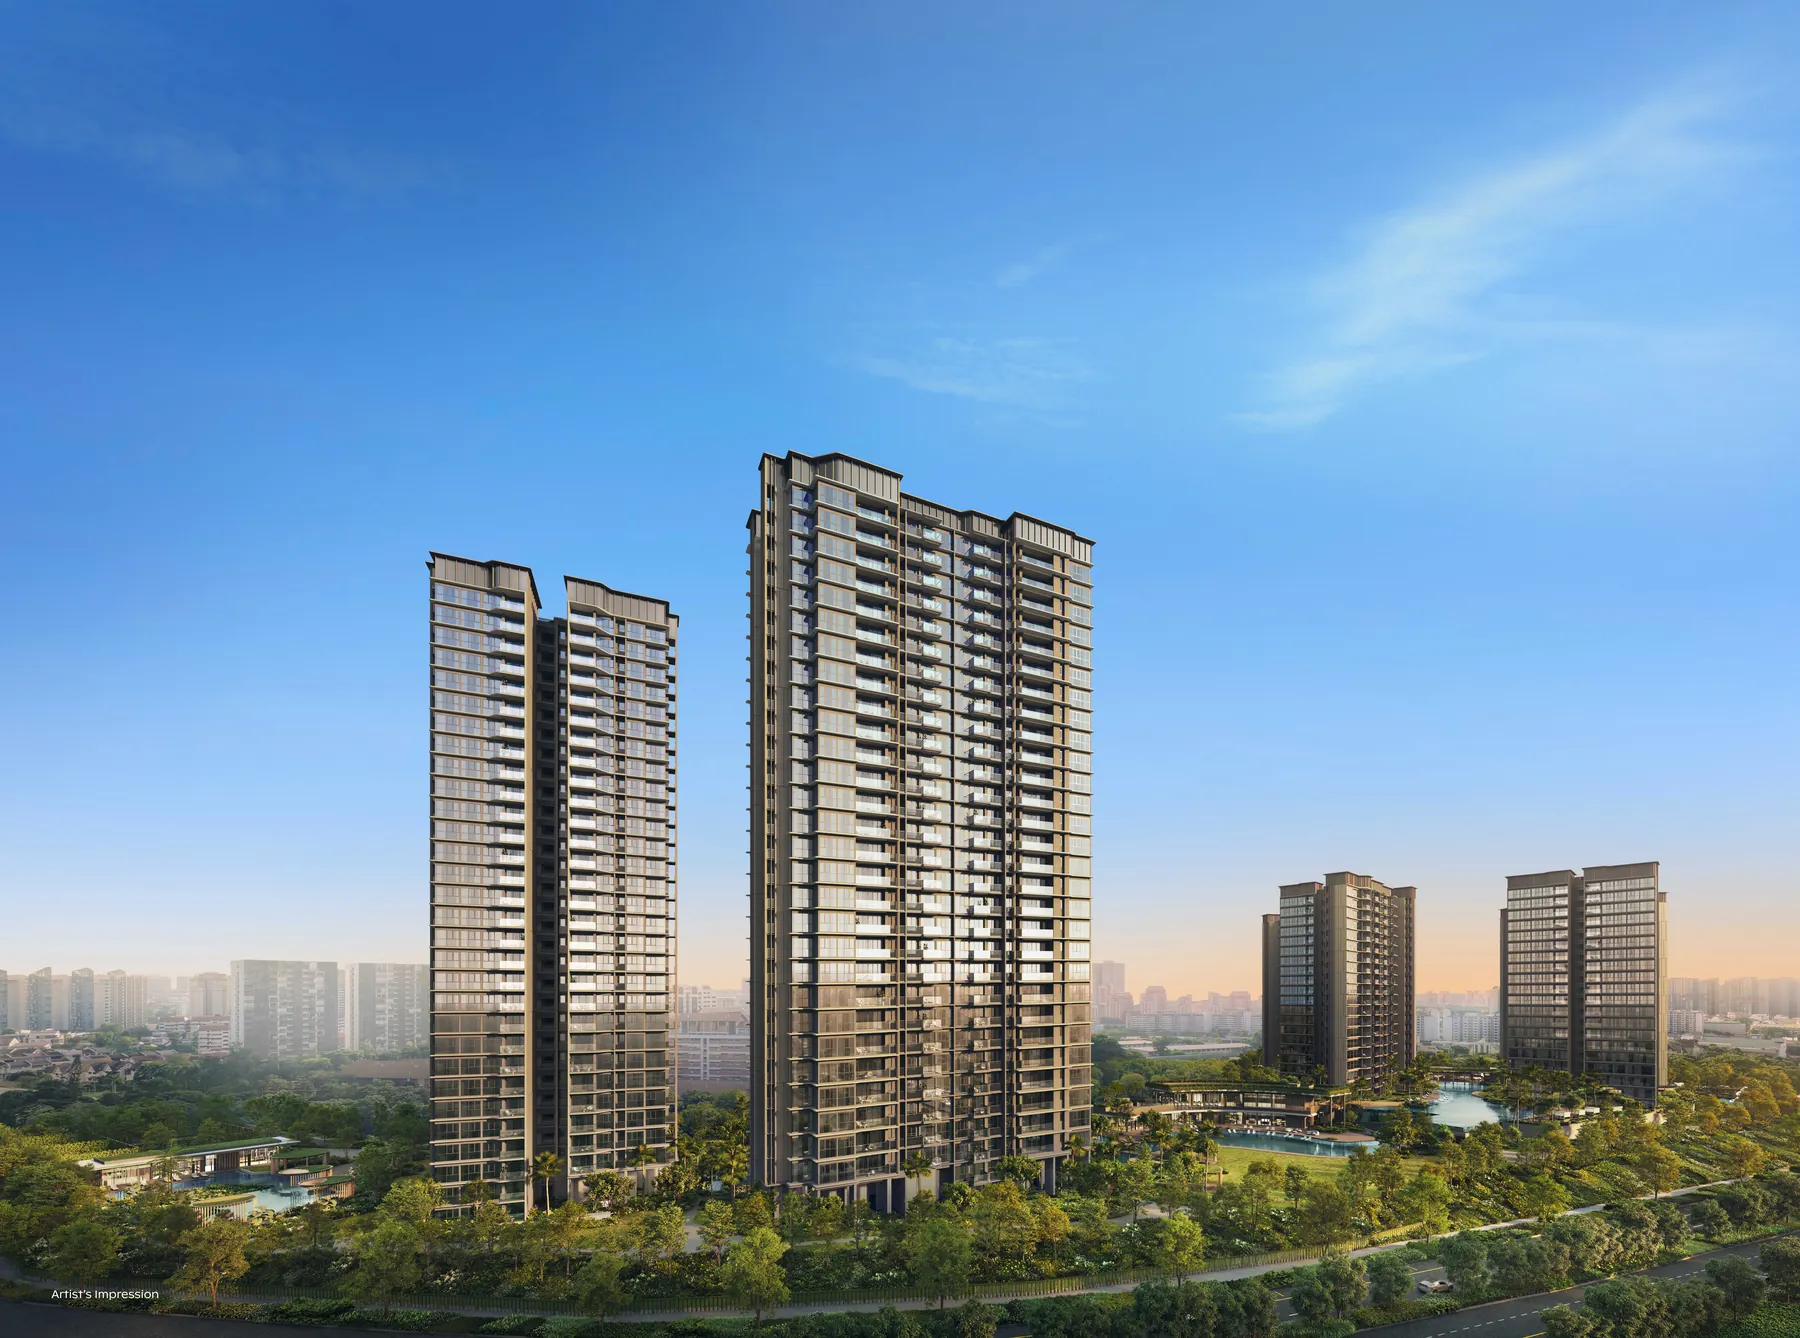
Thomson Reserve is a 1,268-home, 99-year leasehold condominium at Bright Hill Drive in District 20, built by UOL Group, Singapore Land Group and CapitaLand Development. The land was secured in November 2024 at $1,178 psf ppr. Upper Thomson MRT is a four-minute walk and running today. Preview is targeted for October 2026, with completion around 2031.
Key Takeaways
- Land secured at $1,178 psf ppr in November 2024. Every comparable central-region site awarded since cost $1,278 to $1,820, or 8% to 55% more.
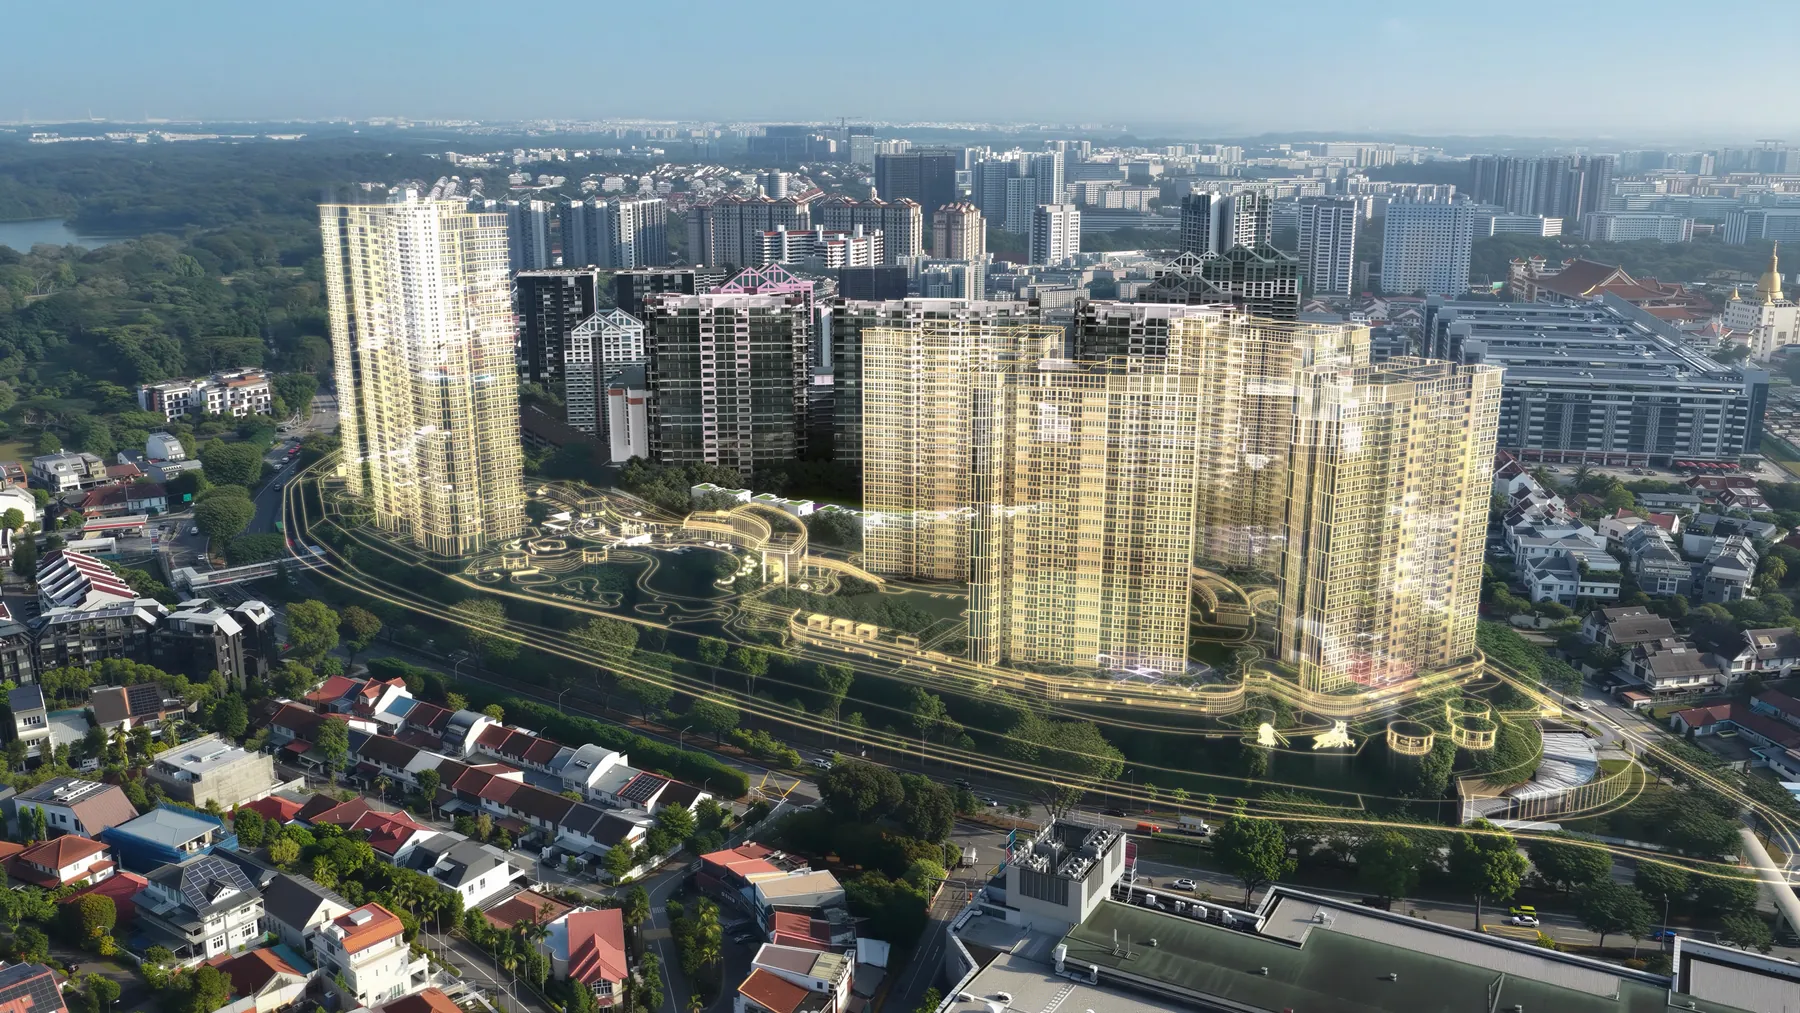
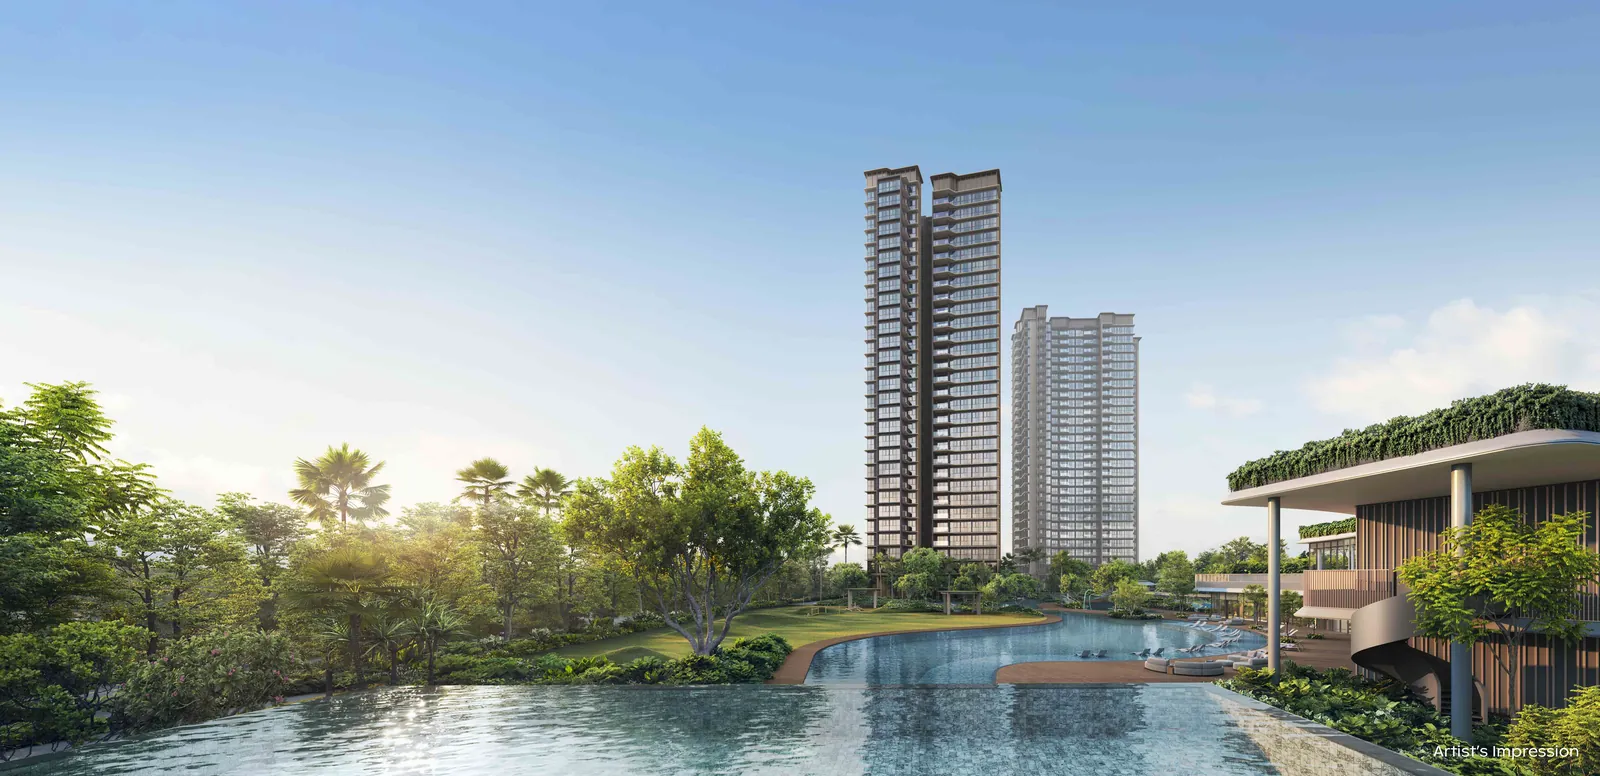
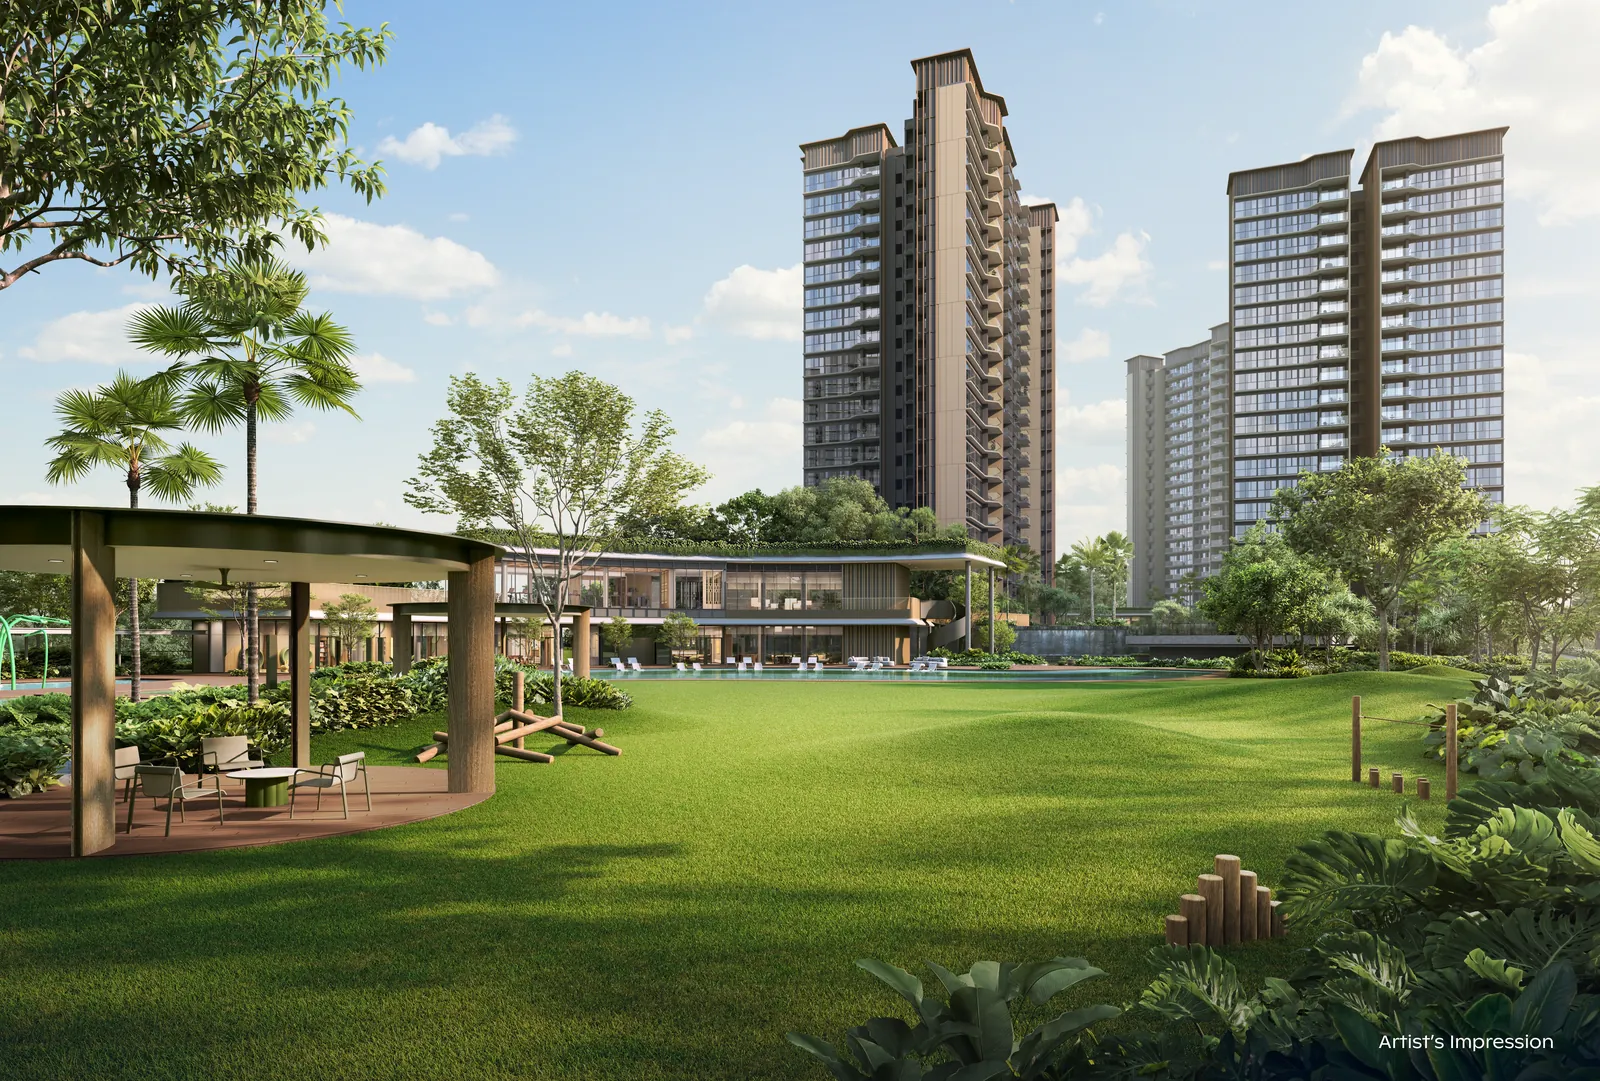
- 1,268 homes across six towers, two of 30 storeys and four of 21, on a site of roughly 5 hectares.
- Unit mix is developer-confirmed: 84% two and three-bedroom, 16% four and five-bedroom.
- Three clubhouses and more than 80 facilities, per the developer's own presentation.
- Upper Thomson (TE8) is about 0.27km away. Bright Hill becomes a Cross Island Line interchange, targeted 2030.
- My working launch estimate is $2,370 to $2,680 psf. No developer price list exists yet.
This is the launch I get asked about most often this year.
Usually in the same two words: worth it?
Not because it is the biggest, although at 1,268 homes it is.
Because of what the land cost the developer, and what that does or does not mean for the person buying it.
| Item | Detail |
|---|---|
| Name | Thomson Reserve, on the former Thomson View site |
| Address | Bright Hill Drive, District 20 |
| Developers | CapitaLand Development, UOL Group and Singapore Land Group, through Tamarind Development Pte Ltd |
| Market segment | Rest of Central Region, the city fringe |
| Tenure | Fresh 99-year lease. The start date is fixed only on legal completion |
| Total homes | 1,268 |
| Towers | Six. Two of 30 storeys, four of 21 storeys |
| Site area | About 5 hectares, roughly 504,300 sq ft (derived from allowed floor space ÷ plot ratio) |
| Plot ratio | 2.1 |
| Facilities | Three clubs and more than 80 facilities: Island Club, Grand Clubhouse, Wellness Club |
| Carpark | About 1,014 lots, as reported in July 2026 and not yet developer-published |
| Land cost | $1,178 psf ppr. Sale price $810 million, cleared by the High Court on 1 July 2025 |
| Estimated breakeven | $2,058 psf ppr (est.) |
| Estimated launch price | $2,370 to $2,680 psf (est.). No developer price list exists |
| Preview | Targeted 3 or 10 October 2026 (est.). Neither date is confirmed |
| Completion | Around 2031 (est.) |
| Nearest MRT | Upper Thomson (TE8), about 0.27km, roughly a 4-minute walk |
| Second MRT | Bright Hill (TE7), about 0.82km. Becomes a Cross Island Line interchange, targeted 2030 |
| Nearest primary school | Ai Tong School, about 0.57km in a straight line (est.) |
Watch The Developer's Own Teaser
Before the numbers, here is what the developer is actually promising.
The official Thomson Reserve teaser, published by the developer. Artist's impressions throughout; treat it as intent, not as a specification.
Six terms used on this page
psf ppr means dollars per square foot per plot ratio. It is what a developer pays for land, measured against the floor space allowed on it. Think of it as the land cost buried inside every square foot of finished home.
Plot ratio is how much floor space may be built, as a multiple of the land area. A plot ratio of 2.1 on 504,300 sq ft of land allows about 1,059,000 sq ft of floor space.
Breakeven is the total cost of building and selling the project, divided by that floor space. It is the price below which the developer loses money.
En bloc is a collective sale. The owners of an old estate agree to sell the whole site to a developer at once.
Rest of Central Region is the middle ring on the government's three-way map of Singapore. It sits between the prime core and the suburbs.
TOP stands for Temporary Occupation Permit. It is the point at which a building is safe to move into, and when you collect keys.
2. Why Was This Land So Cheap?
For where that land cost sits against the rest of the 2026 market, including the record $1,556 psf ppr paid at Dover Drive in March, I set out the wider picture in my market outlook for the rest of 2026.
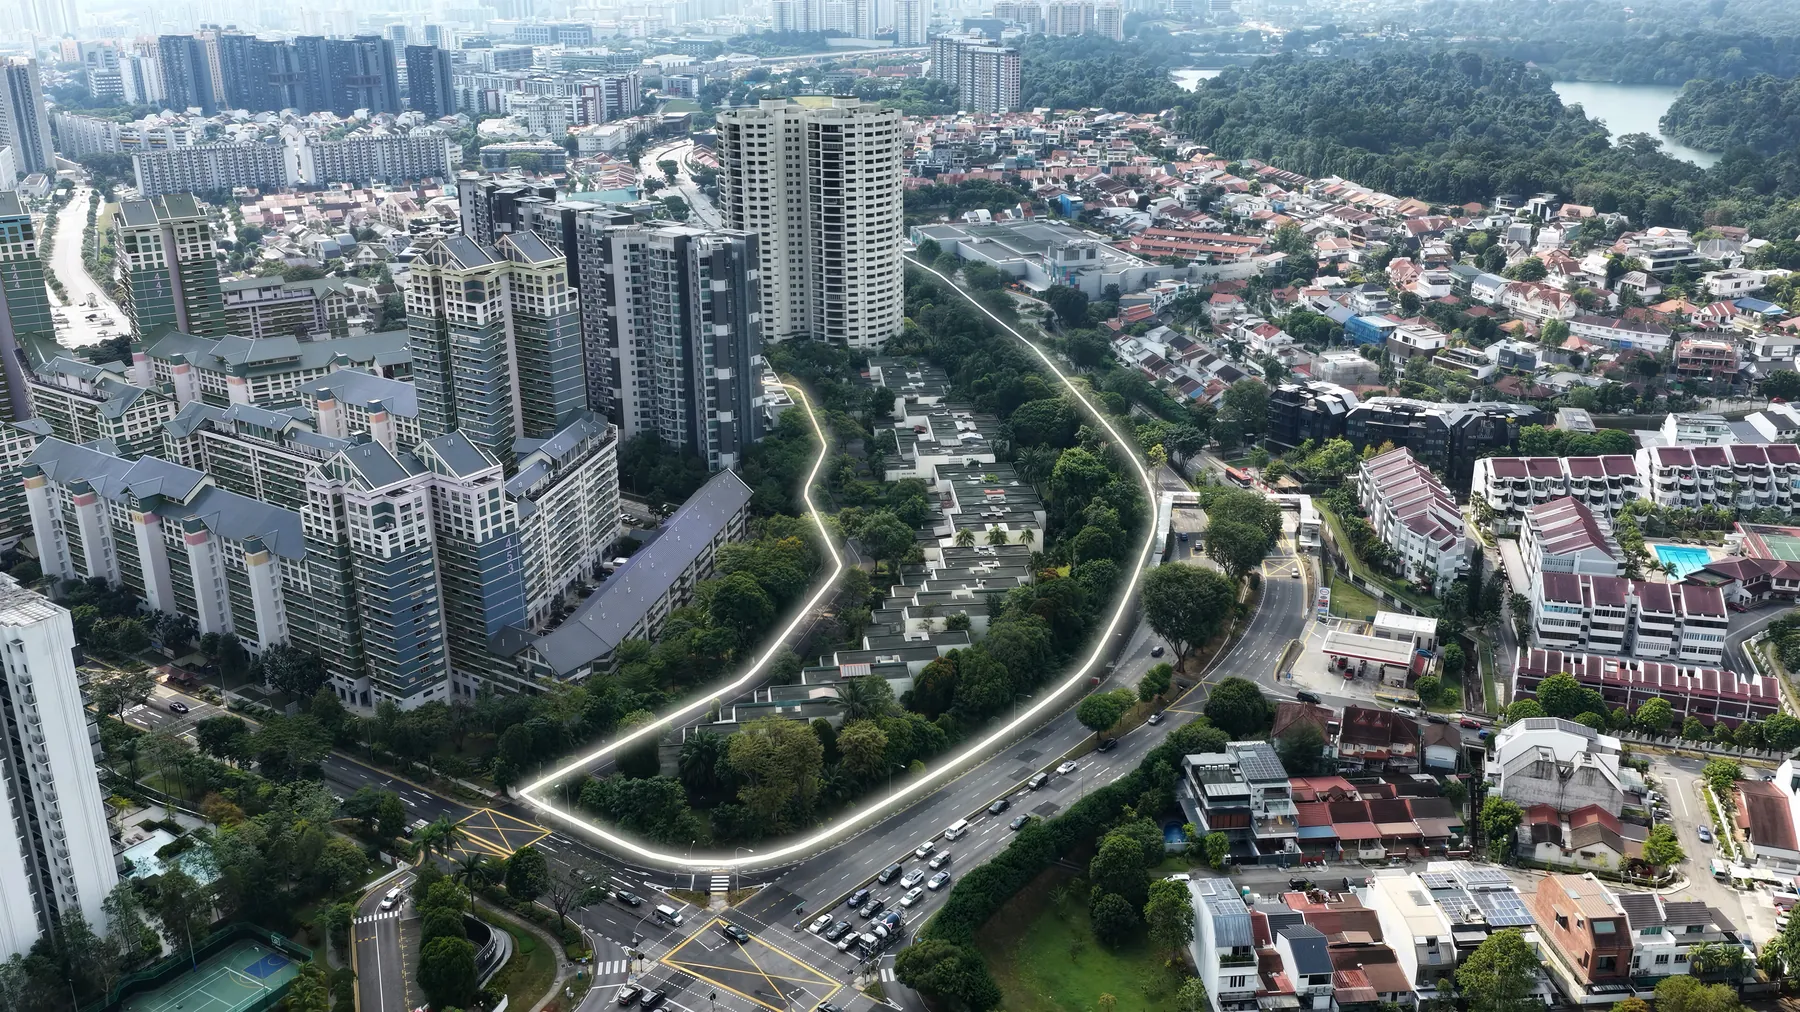
A seventeen-year en bloc.
Thomson View Condominium was completed in 1987, on a lease that began in 1975.
It held 255 homes and one shop.
Its owners tried to sell the site as one block five times.
Four attempts failed.
The fifth worked, but only after the asking price came down.
In July 2024 the site was relaunched at $918 million, following an April tender that closed without a deal.
In October 2024 the consortium exercised a call option at $810 million.
That is a cut of about $108 million, or roughly 11.8% off the original ask.
Enough owners signed by November 2024, and the sale was awarded on 25 November.
A small group of owners then objected, and a stop order followed in March 2025.
The High Court granted the sale order on 1 July 2025.
Here is the part most write-ups skip.
The $810 million went to the owners.
It is not the full land bill.
Two government charges sit on top of it: a land betterment charge for building more floor space than the old site had, and a lease upgrading premium to reset the lease to a fresh 99 years.
Add both and the total land outlay comes to roughly $1,247.6 million (est.).
Divide that by the floor space allowed, and you get the $1,178 psf ppr figure everyone quotes.
So a buyer at the October preview is buying on land priced in a year when almost nobody else was bidding for this site.
That is not a marketing line. It is a done deal, on the public record, and it cannot be revised upwards.
The same three developers went on to top the Bedok tender on 1 September 2026 at $1,537 psf ppr, a record land rate for a suburban state site. I work through what that New Upper Changi Road bid signals for Thomson Reserve's October pricing separately, because the short answer is not the obvious one.
Closer to home, the state plot opposite Ai Tong School on Sin Ming Avenue drew a top bid of $1,612 psf ppr on 15 September 2026. That is $434 more than Thomson Reserve's land. My analysis of the Lorong Puntong GLS bid near Bright Hill MRT covers why developers are paying that much, and what the future project could cost.
Further up the Thomson corridor, a Sustained Land-led consortium secured a District 11 plot in August 2026 at $1,297 psf ppr. That deal, and what the 8 Thomson Lane land cost implies for its eventual launch price, is the closest recent read on how cheap central land can still be bought when a site never goes to tender.
3. Will The Developer Actually Pass That Discount On?
Partly. And partly is enough.
The instinct whenever a cheap land cost gets quoted is:
“Cheap land just means a fatter margin for the developer. Nothing reaches me.”
I understand the suspicion, and it is half right.
A lower land cost lowers the floor under the price. It does not lower the ceiling.
But look at what the floor actually does in a competitive launch.
Start with the land. Add construction, financing, professional fees, taxes and marketing. Divide by the floor space. That total is the breakeven.
| Cost item | Estimate |
|---|---|
| Land, including charges and lease premium | $1,247.6m |
| Construction | $413m |
| Land financing | $197m |
| Professional fees, legal and taxes | $199m |
| Marketing and other costs | $123m |
| Total cost | $2,179.8m |
| Breakeven | $2,058 psf ppr (est.) |
Floor space allowed: 98,391 sqm × 10.7639 = 1,059,076 sq ft.
Land: $1,247,600,000 ÷ 1,059,076 sq ft = $1,178 psf ppr. Matches.
Breakeven: $2,179,800,000 ÷ 1,059,076 sq ft = $2,058 psf ppr. Matches.
Launch range: $2,058 × 1.15 = $2,367. $2,058 × 1.30 = $2,675. Rounded, $2,370 to $2,680 psf.
The 1.15 to 1.30 band is a developer margin of 15% to 30%.
It is the band applied to every project on PropertyInsider, not one chosen to flatter this site.
A second method lands in the same place, which is reassuring.
Across 53 launched projects, the middle one sold at about 2.12 times its land cost. Apply that to $1,178 and you get roughly $2,500 psf, sitting inside the range above.
Now the part that matters for you.
A developer with a $2,058 breakeven can sell at $2,400 and still make money.
A developer whose land cost 30% more cannot.
Cheap land does not guarantee a cheap launch. It guarantees the developer has room to move when the room is needed.
In a soft quarter, room to move is worth a great deal.
Applying the range to typical layout sizes gives the following. Indicative only, not a price list.
| Layout | Typical size | Indicative total price (est.) |
|---|---|---|
| 2-bedroom | 700 sq ft | $1.66m to $1.88m |
| 3-bedroom | 950 sq ft | $2.25m to $2.55m |
| 4-bedroom | 1,150 sq ft | $2.73m to $3.08m |
And here is the fair caveat, stated once and stated plainly.
The land is cheap against what is coming, not against everything already selling.
Set against all 28 city-fringe sites in the dataset, including those on sale now, $1,178 ranks ninth. Eight are cheaper, one of them Artisan 8 in this same District 20.
So the honest version of the land argument is narrower than the headline, and still strong: Thomson Reserve should price below the launches that follow it, not below every home already standing near it.
4. What Does The Unit Mix Tell You?
That it was built for families.
The developer has confirmed the split, and it is the most revealing single table on this page.
| Bedroom type | Number of units | Share |
|---|---|---|
| 2-Bedroom | 1,066 | 84% |
| 2-Bedroom Premium | ||
| 2-Bedroom Premium + Study | ||
| 3-Bedroom | ||
| 3-Bedroom Premium | ||
| 3-Bedroom Premium + Study | ||
| 4-Bedroom | 202 | 16% |
| 4-Bedroom Premium (with Private Lift) | ||
| 4-Bedroom Premium + Study (with Private Lift) | ||
| 5-Bedroom Suite (with Private Lift) | ||
| Total | 1,268 | 100% |
Read that split properly and it tells you three things.
1,066 homes are two and three-bedroom.
That is the range Bishan, Sin Ming and Ang Mo Kio upgraders actually shop in.
A developer aiming at investors builds one and two-bedders. A developer aiming at speculators builds shoebox stock. Neither is what happened here.
Only 202 homes are four and five-bedroom.
Three of those four large layouts come with a private lift, and the 5-Bedroom Suite sits at the top of the range.
Whether that scarcity translates into anything depends entirely on how the developer prices those layouts, which nobody knows yet.
Breadth is the third point, and it is the one buyers underrate.
Ten distinct layouts across six towers means there is genuinely something at your budget rather than a take-it-or-leave-it choice of two floor plans.
That matters most to the upgrader whose bridge is tight.
One honest gap, because it changes what you can plan.
The developer has released the group totals, not a unit count for each of the ten layouts, and no sizes at all.
So nobody can tell you today how many 3-Bedroom Premium + Study units exist, or what they measure.
Both land at preview.
5. Is The Station Really At The Door?
Yes. Four minutes, on a line that runs today.
Thomson Reserve sits on Bright Hill Drive, just off Upper Thomson Road, between Upper Thomson and Bishan.
This is a settled part of Singapore, not a new town waiting to fill in.
The shops, the schools, the food and the parks are all there now.
Distances below are straight lines from an approximate site centre, so read them as a ranking rather than a walking route. Walking times assume a steady pace with an allowance for street routing.
| Place | Straight line | Estimated walk |
|---|---|---|
| Thomson Plaza (shopping mall) | 0.16 km | 2 min |
| Upper Thomson MRT (TE8) | 0.27 km | 4 min |
| Ai Tong School | 0.57 km | 9 min |
| Thomson Community Club | 0.79 km | 12 min |
| Shunfu Mart hawker centre | 0.80 km | 12 min |
| Bright Hill MRT (TE7) | 0.82 km | 12 min |
| Windsor Nature Park | 1.09 km | 16 min |
| Bishan-Ang Mo Kio Park | 1.18 km | 18 min |
| Marymount MRT (CC16) | 1.28 km | 19 min |
| Eunoia Junior College | 1.33 km | 20 min |
| MacRitchie Reservoir | 1.48 km | 22 min |
| Mount Alvernia Hospital | 1.72 km | 26 min |
Two things on that table deserve more weight than they usually get.
The mall is closer than the station.
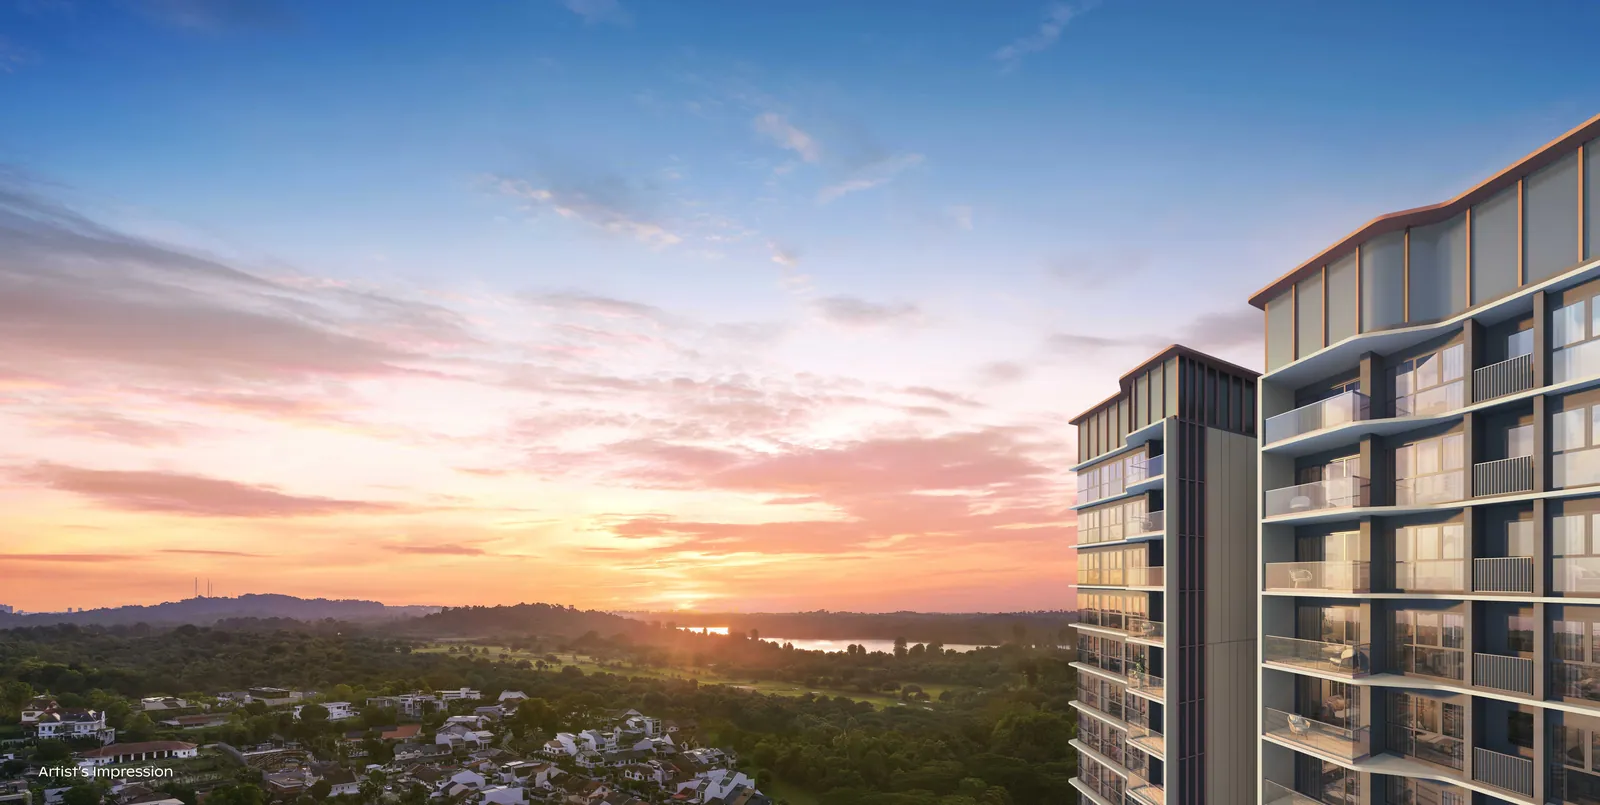
And the Central Catchment Nature Reserve sits behind the estate.
That reserve holds more than 2,000 hectares of forest and more than 20 kilometres of trails around MacRitchie and the wider network.
It is gazetted land, not a plot waiting for a tender.
Which means the green view is protected by law rather than by hope.
Now the honest limit of the location story.
This is not a transformation precinct.
There is no Tengah or Bidadari masterplan here, because Bishan and Upper Thomson were built out decades ago.
You are buying a finished neighbourhood rather than a promised one.
For a family with a school run and a commute, that is the better trade, and I would rather have it than a render of a town centre due in 2034.
6. What Changes Here In 2030?
A second MRT line.
Upper Thomson (TE8) is about a four-minute walk and has run on the Thomson-East Coast Line since August 2021. From there you reach Orchard, the city centre and Marina Bay without changing trains.
Bright Hill (TE7) is about twelve minutes on foot. Its Thomson-East Coast Line platforms run today, and its Cross Island Line platforms are under construction.
The first stage of the Cross Island Line is targeted for 2030, and the construction contract was awarded back in 2022.
So this is a funded, dated commitment rather than a line on a masterplan.
Bright Hill is the point where the Cross Island Line physically meets the Thomson-East Coast Line, which makes it an interchange rather than another stop.
Marymount (CC16) on the Circle Line is about nineteen minutes on foot, or a short bus ride, putting Bishan and the North-South Line within one transfer.
By road, the Central Expressway is a short drive through Marymount and Braddell Roads.
Here is the discipline I apply to any line that has not opened.
Ask whether the case still works if the line is late.
Here it does, because the Thomson-East Coast Line station is already open and four minutes away.
Treat 2030 as the upside, not the foundation. Very few addresses in Singapore sit within a walk of two lines, and fewer still where one of them already runs.
7. Is It Really Within 1km Of Ai Tong School?
Yes, on my measurement.
Ai Tong School sits about 0.57km away in a straight line, so it falls inside the 1km band.
That distance is worked out from map coordinates. The Ministry of Education measures on its own basis, so confirm your exact block with the MOE SchoolFinder before you rely on it.
The more useful question is what being inside 1km actually buys.
The answer is a place in a ballot, not a place at the school.
In the 2025 Primary 1 exercise, Ai Tong balloted at three phases. At Phase 2C, the stage open to families with no prior link to the school, there were 76 applicants for 43 places, and every one of those applicants was a Singapore Citizen living within 1km.
So roughly four in ten of them lost.
Living further than 1km away gave you no practical route in at all that year.
| School | Distance (est.) | P1 demand |
|---|---|---|
| Ai Tong School | 0.57 km | Very high. Balloted at Phases 2A, 2B and 2C |
| Catholic High School | 1.56 km | Very high. Balloted within 1km at 2B and 2C |
| Ang Mo Kio Primary School | 1.70 km | Places available at every phase |
| CHIJ St. Nicholas Girls' School | 2.00 km | Very high. Balloted within 1km at 2B and 2C |
And now a finding of my own that cuts against the usual sales pitch, because you should hear it from me rather than discover it later.
I mapped all 182 MOE primary schools against 107 tracked launches.
In the suburbs, homes within 1km of a very high demand school cost about 4.6% more.
In the city fringe, where Thomson Reserve sits, it runs the other way. Those homes came out about 4.3% cheaper.
What does hold up in both rings is buyer mix rather than price. Homes inside a strong catchment show a 7.2 percentage point higher share of HDB upgraders.
So do not pay a premium for the catchment.
Buy the catchment because your child will walk to school for six years, and take the deeper, more settled pool of future buyers as the bonus.
That is the version I would want told to me.
8. What Are You Actually Getting Inside The Gates?
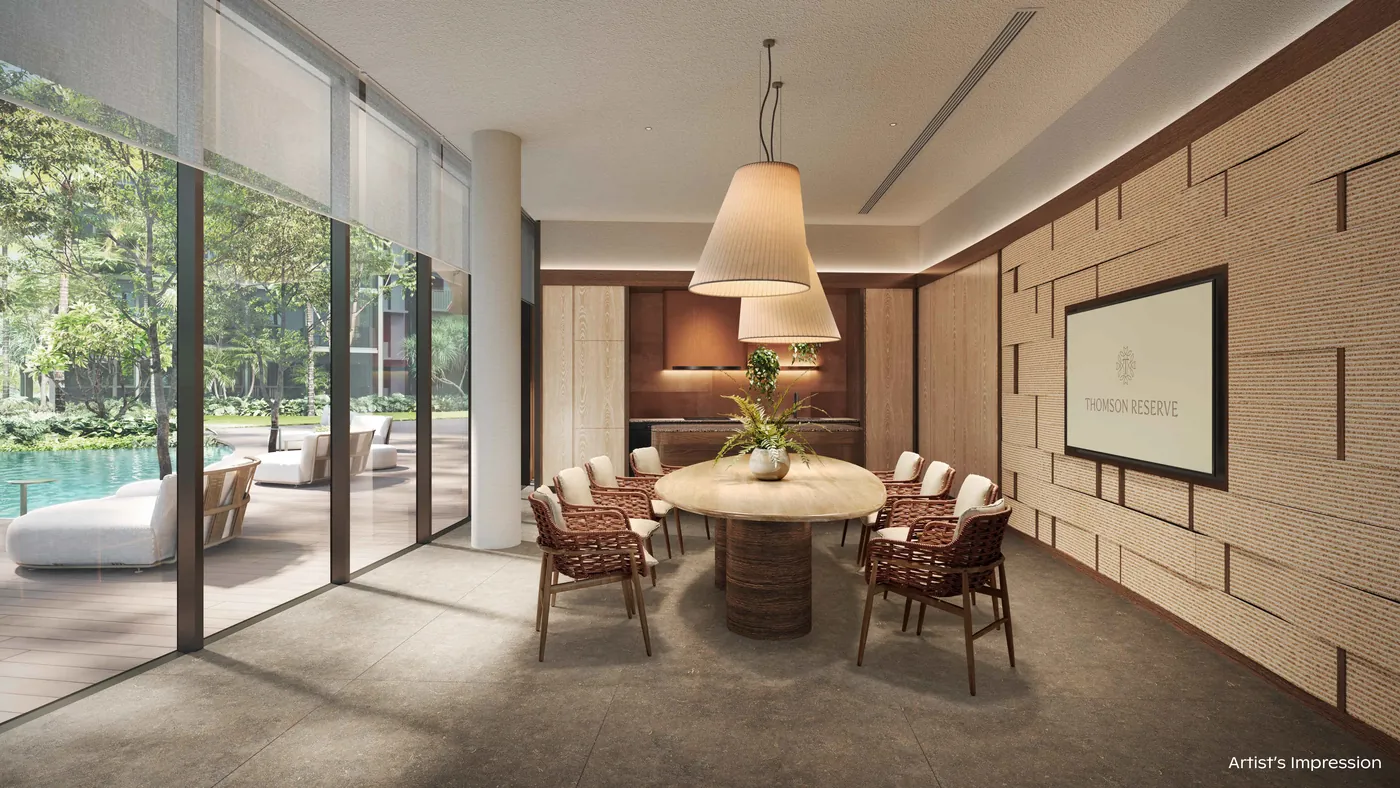
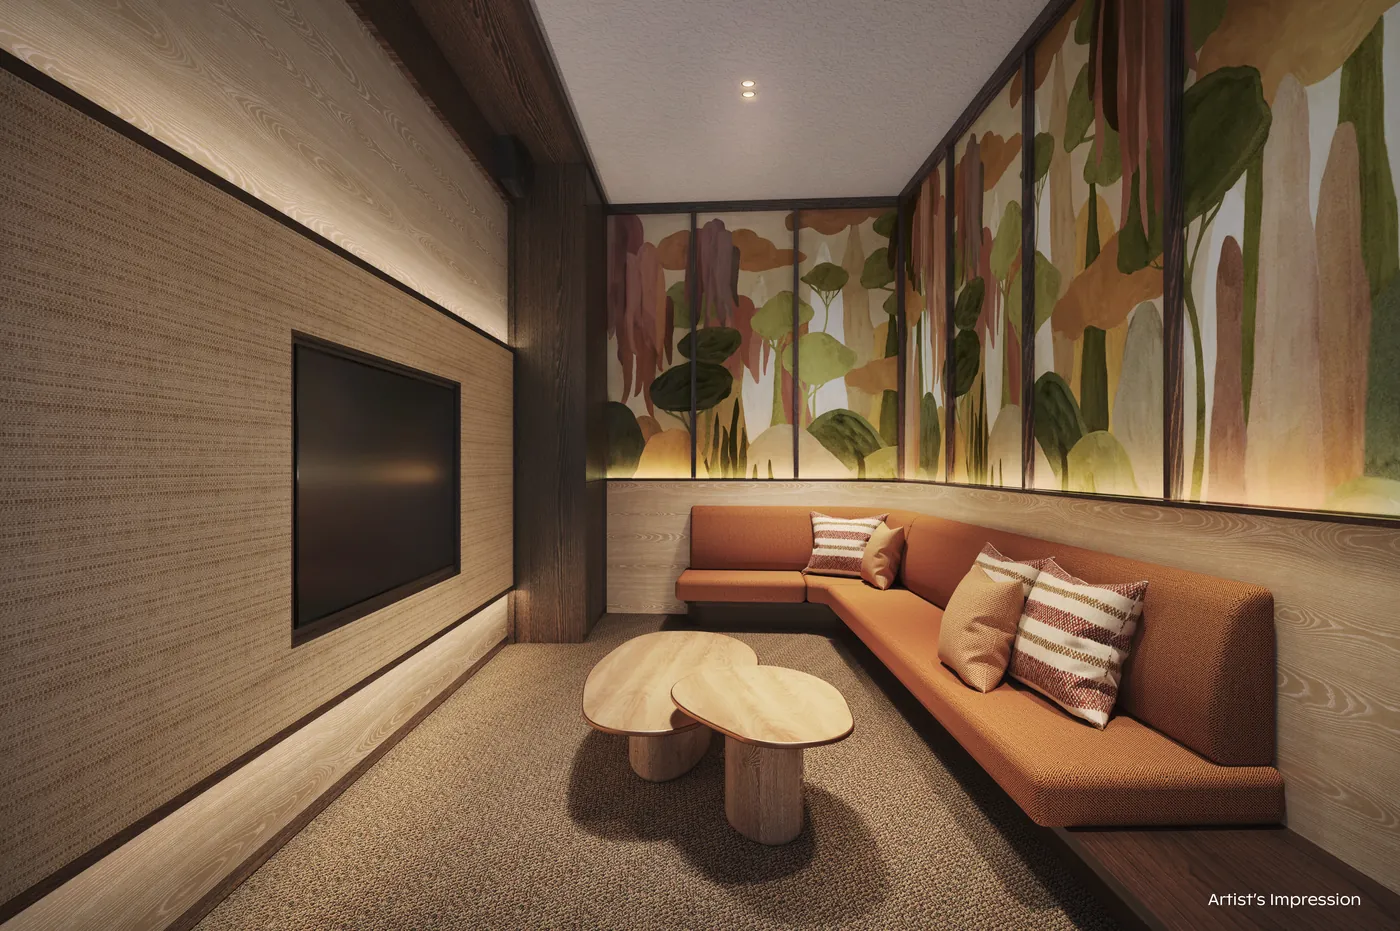
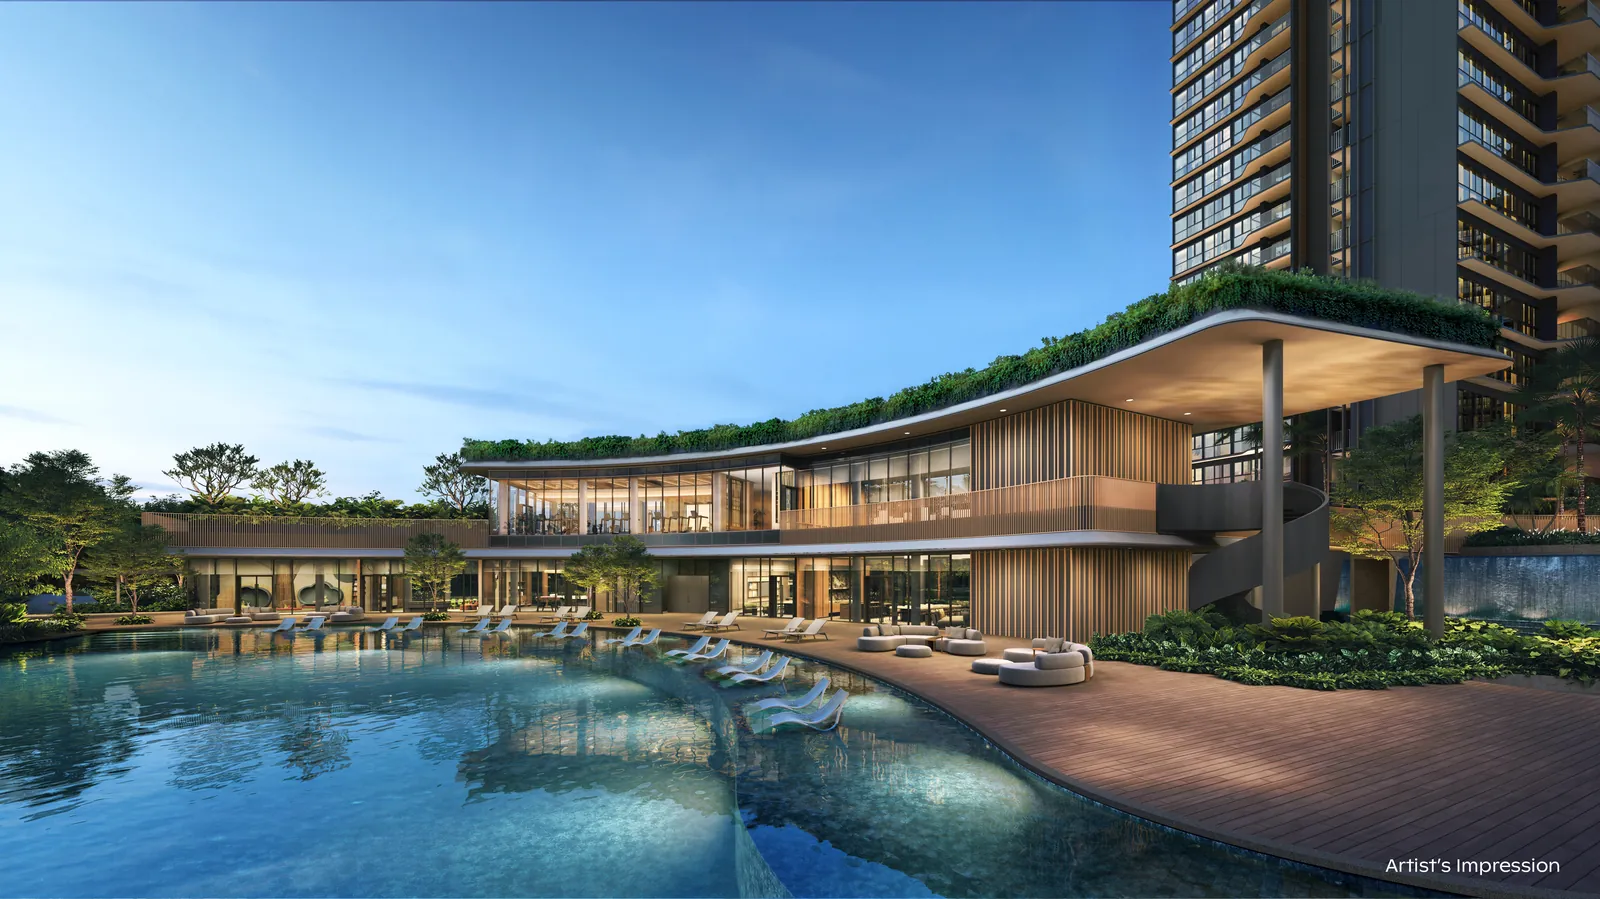
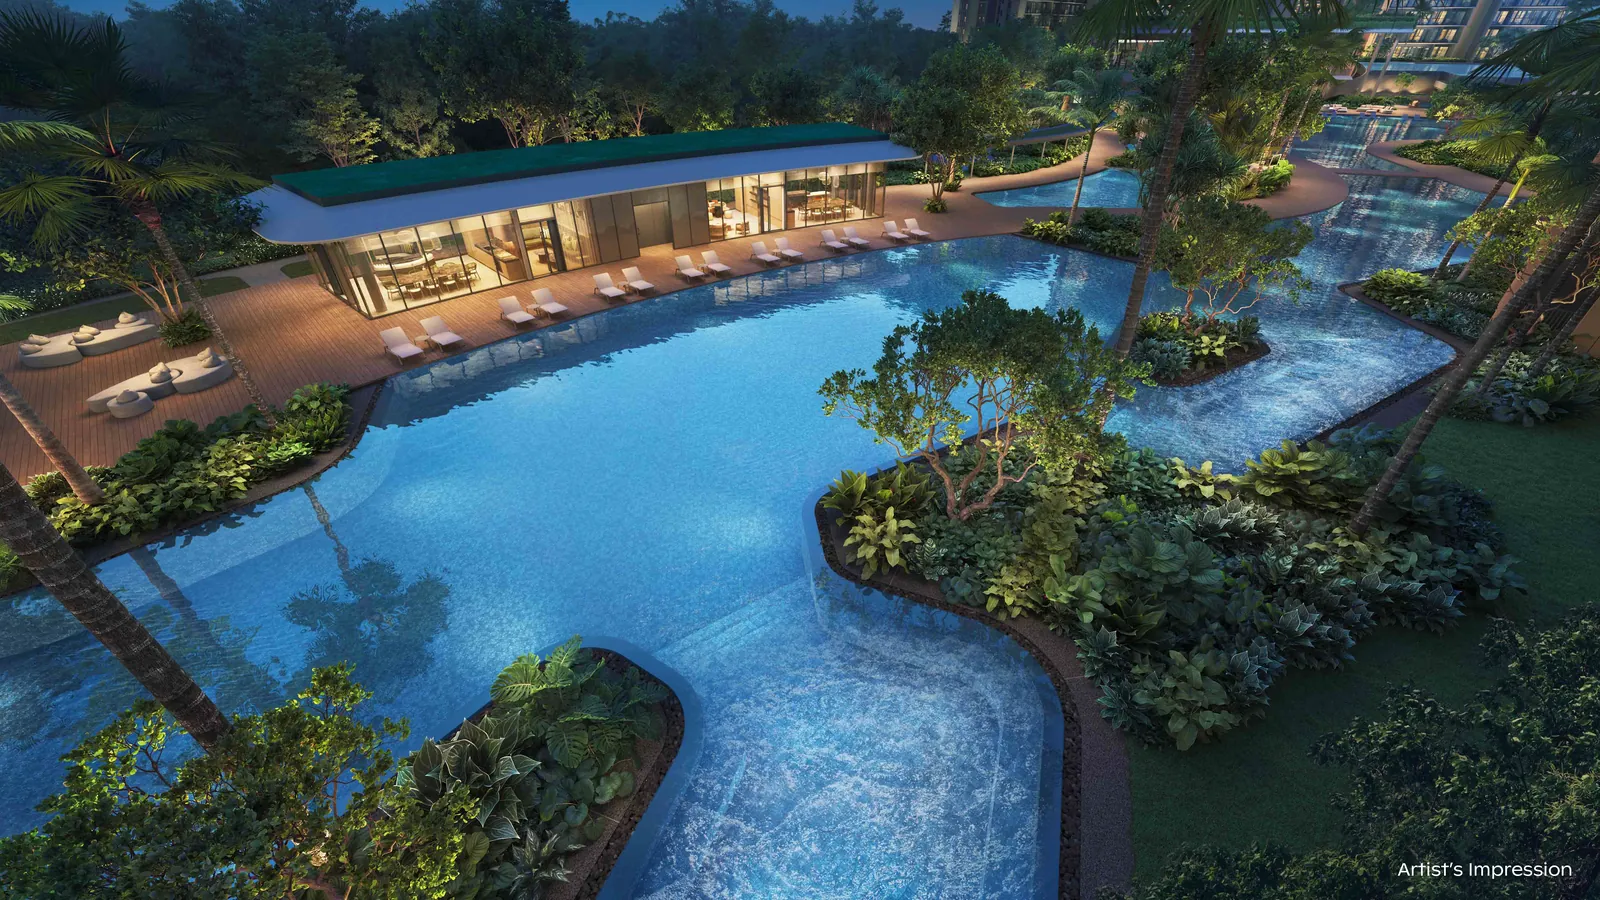
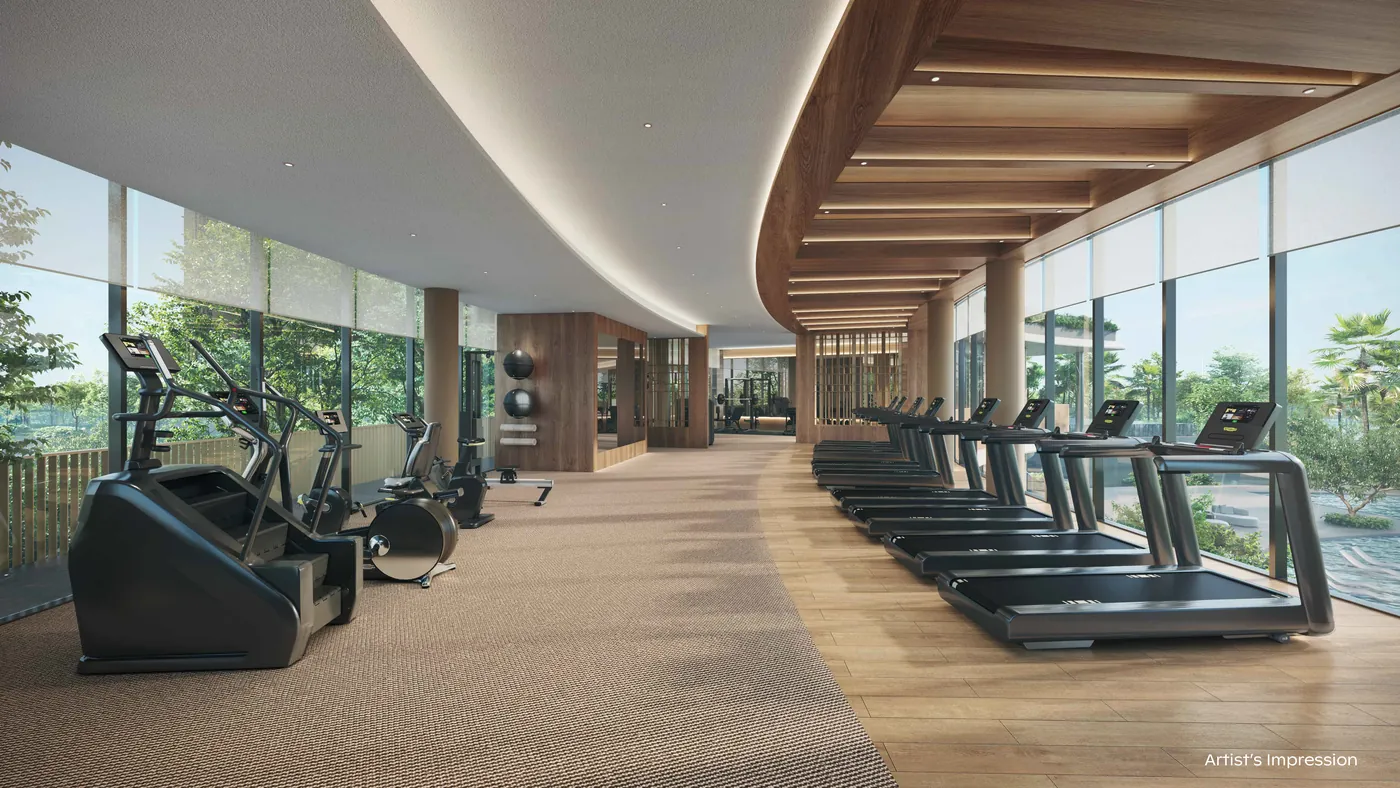
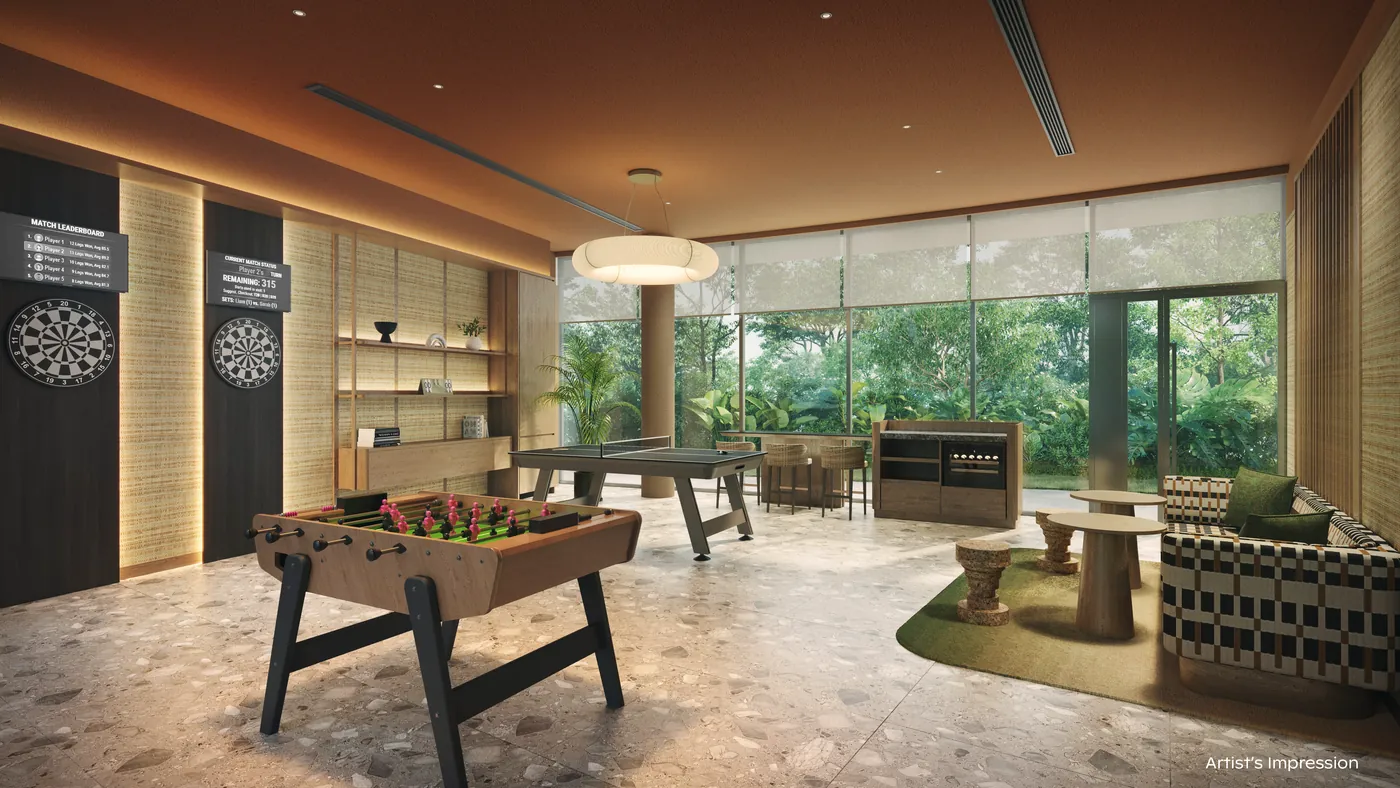
Three clubs, and more than eighty facilities.
This is the part of a launch that is easiest to oversell, so here it is as plainly as I can put it.
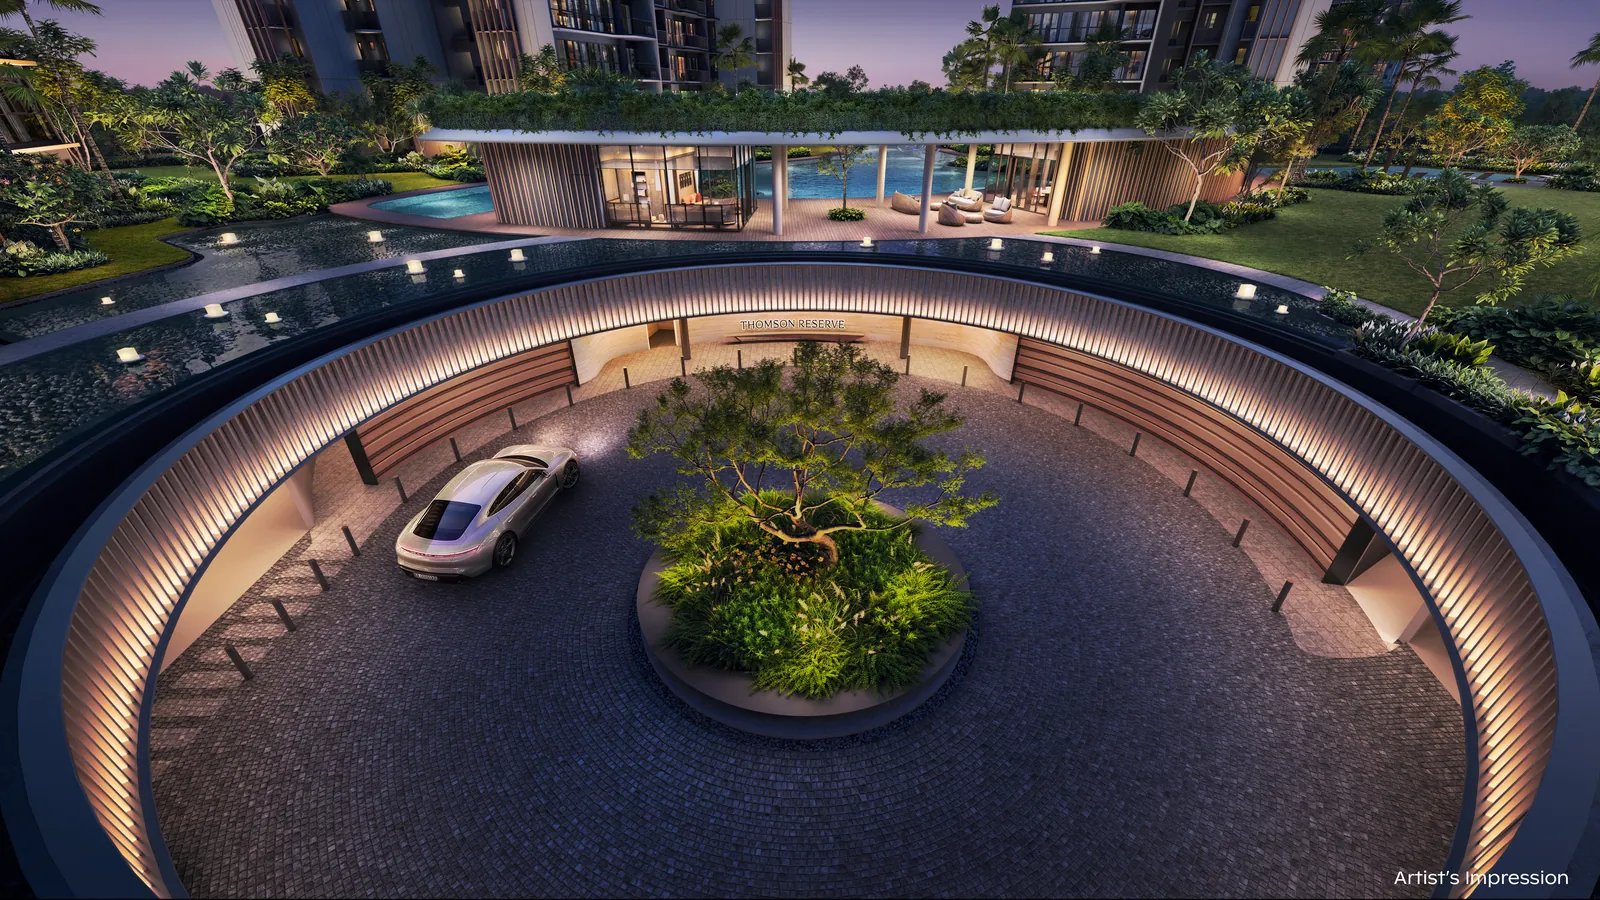
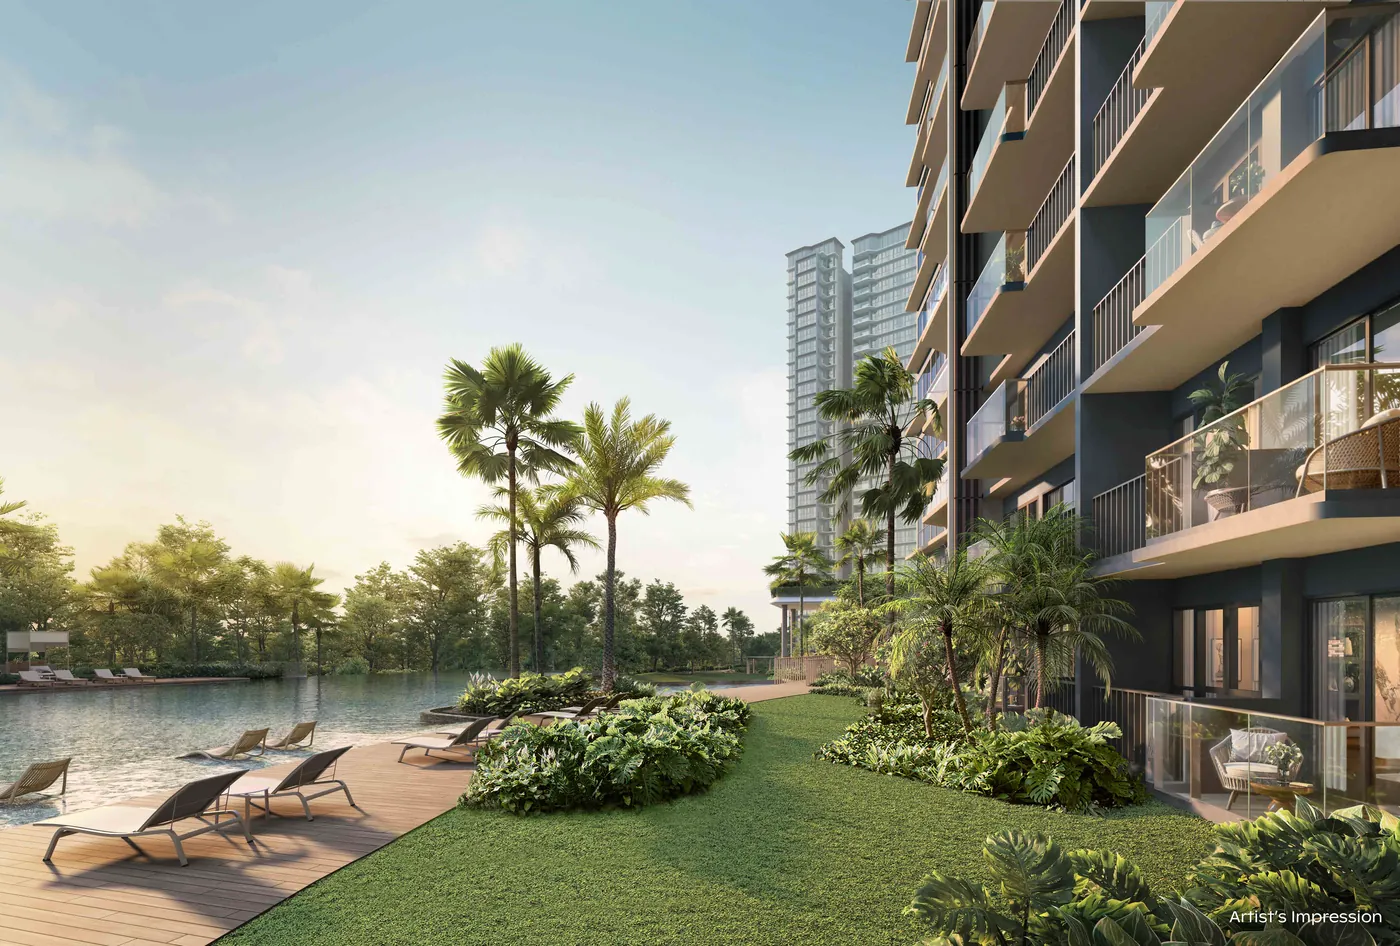
The developer has organised the grounds into three named clubs across roughly 5 hectares, described in its own materials as a green canvas spanning about seven football fields.
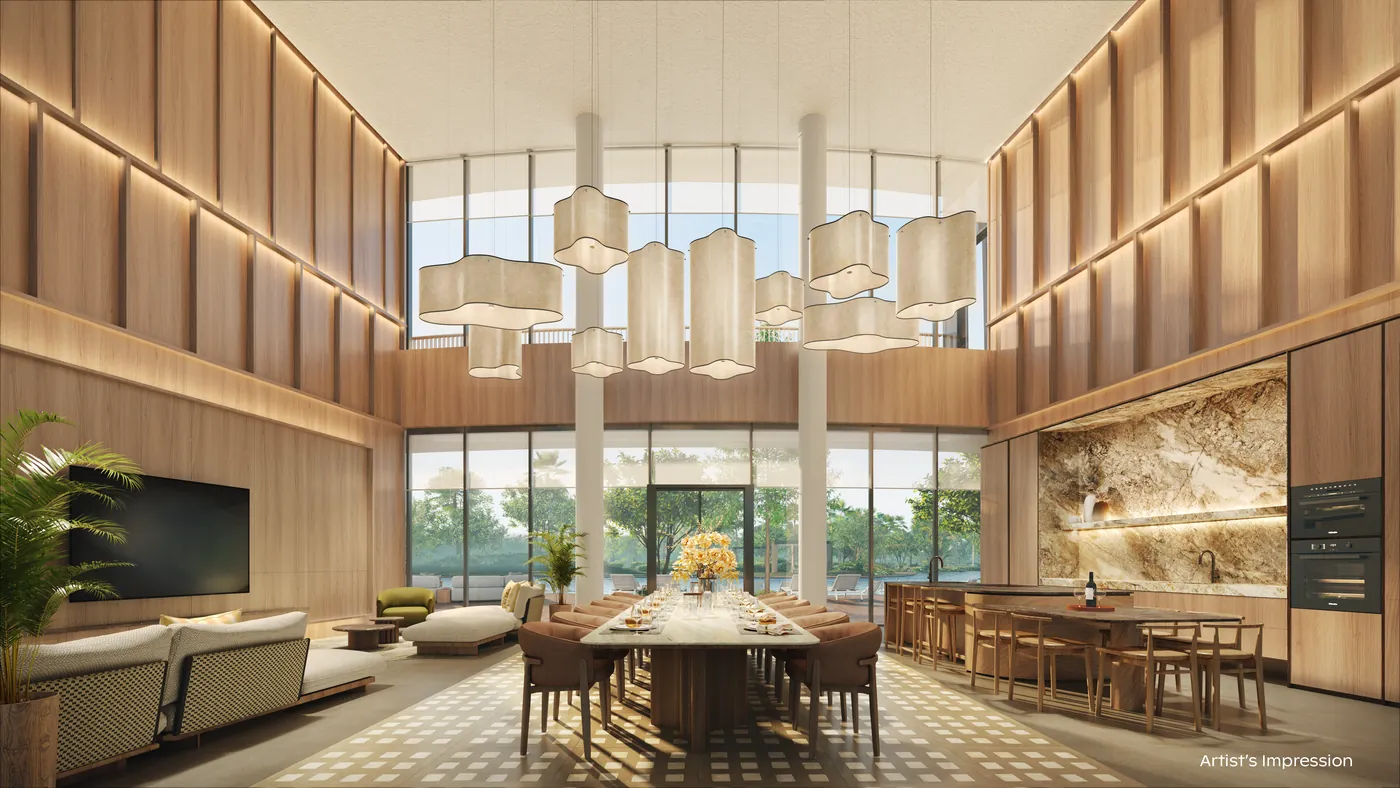
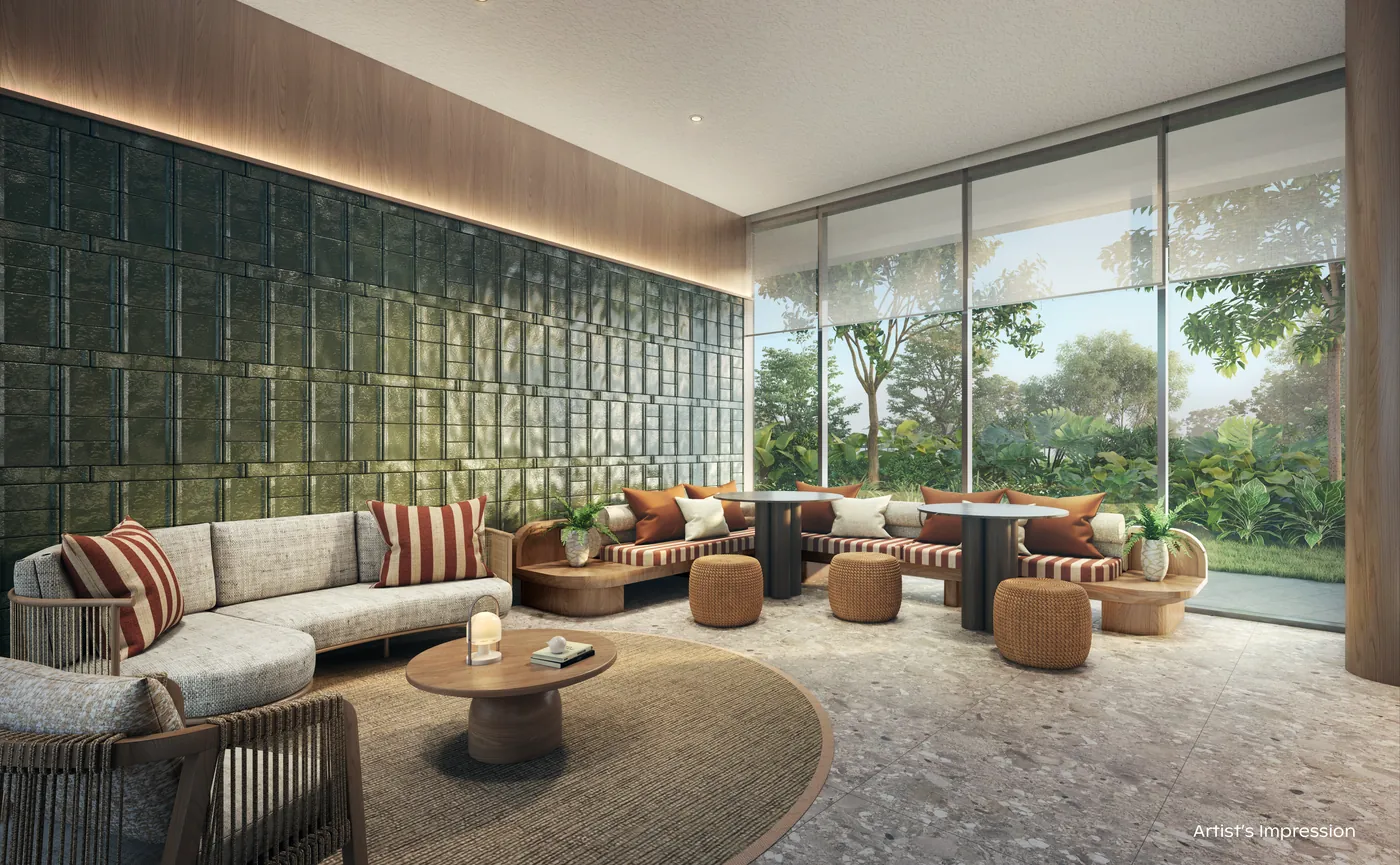
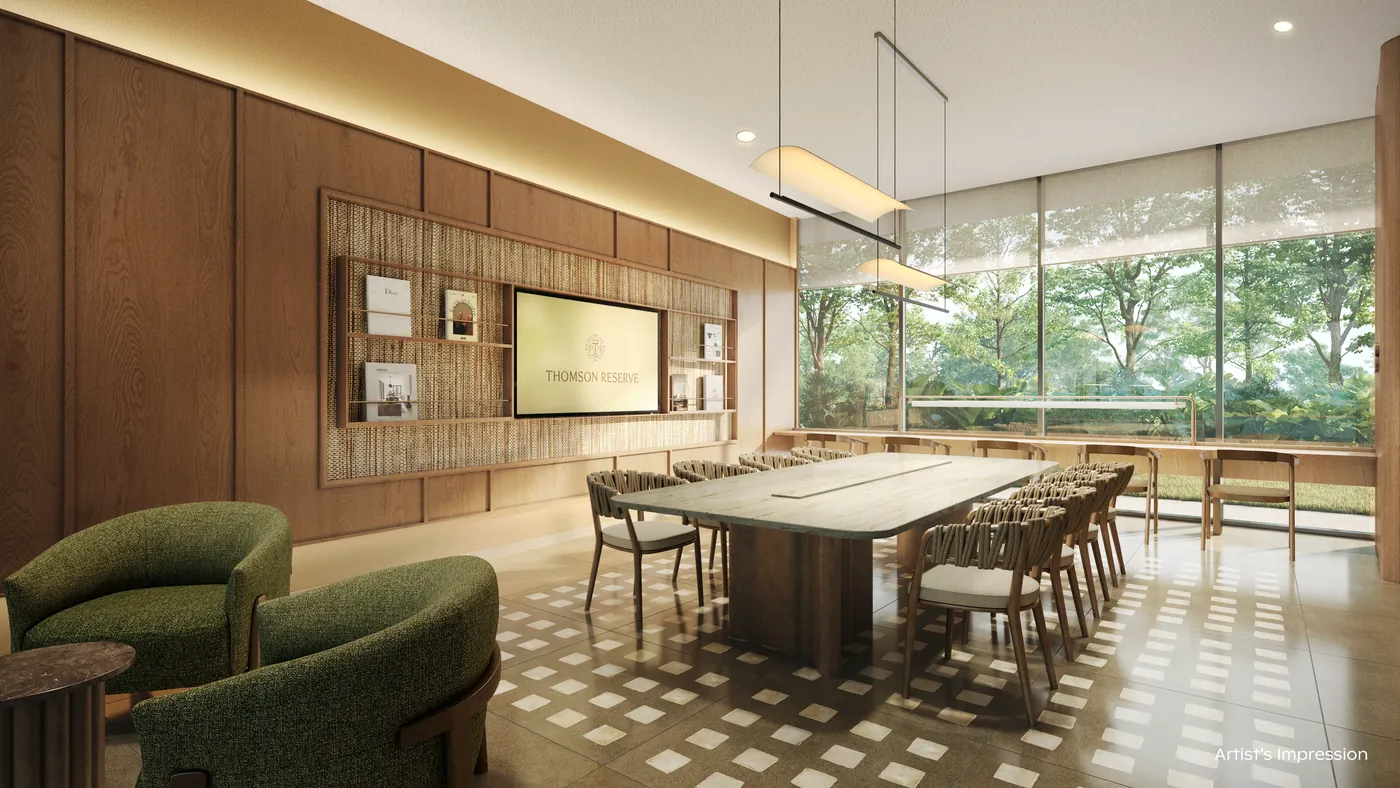
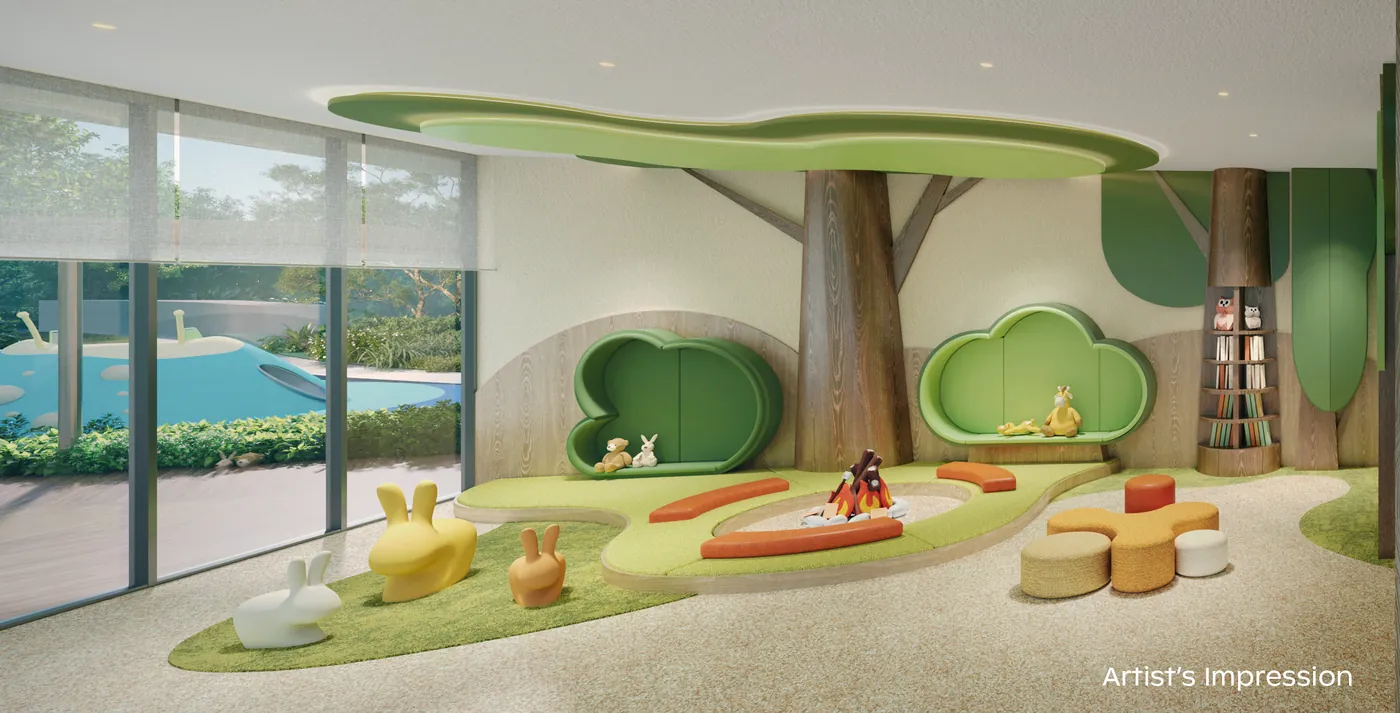
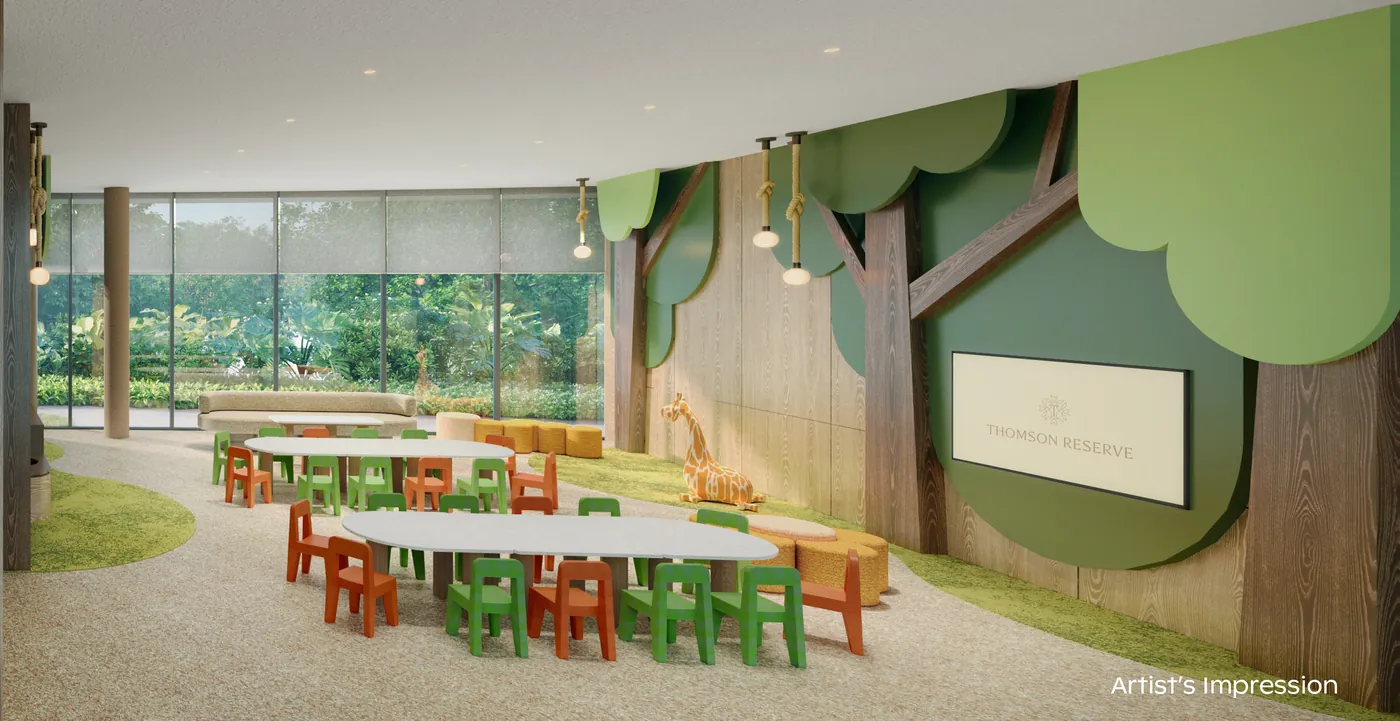
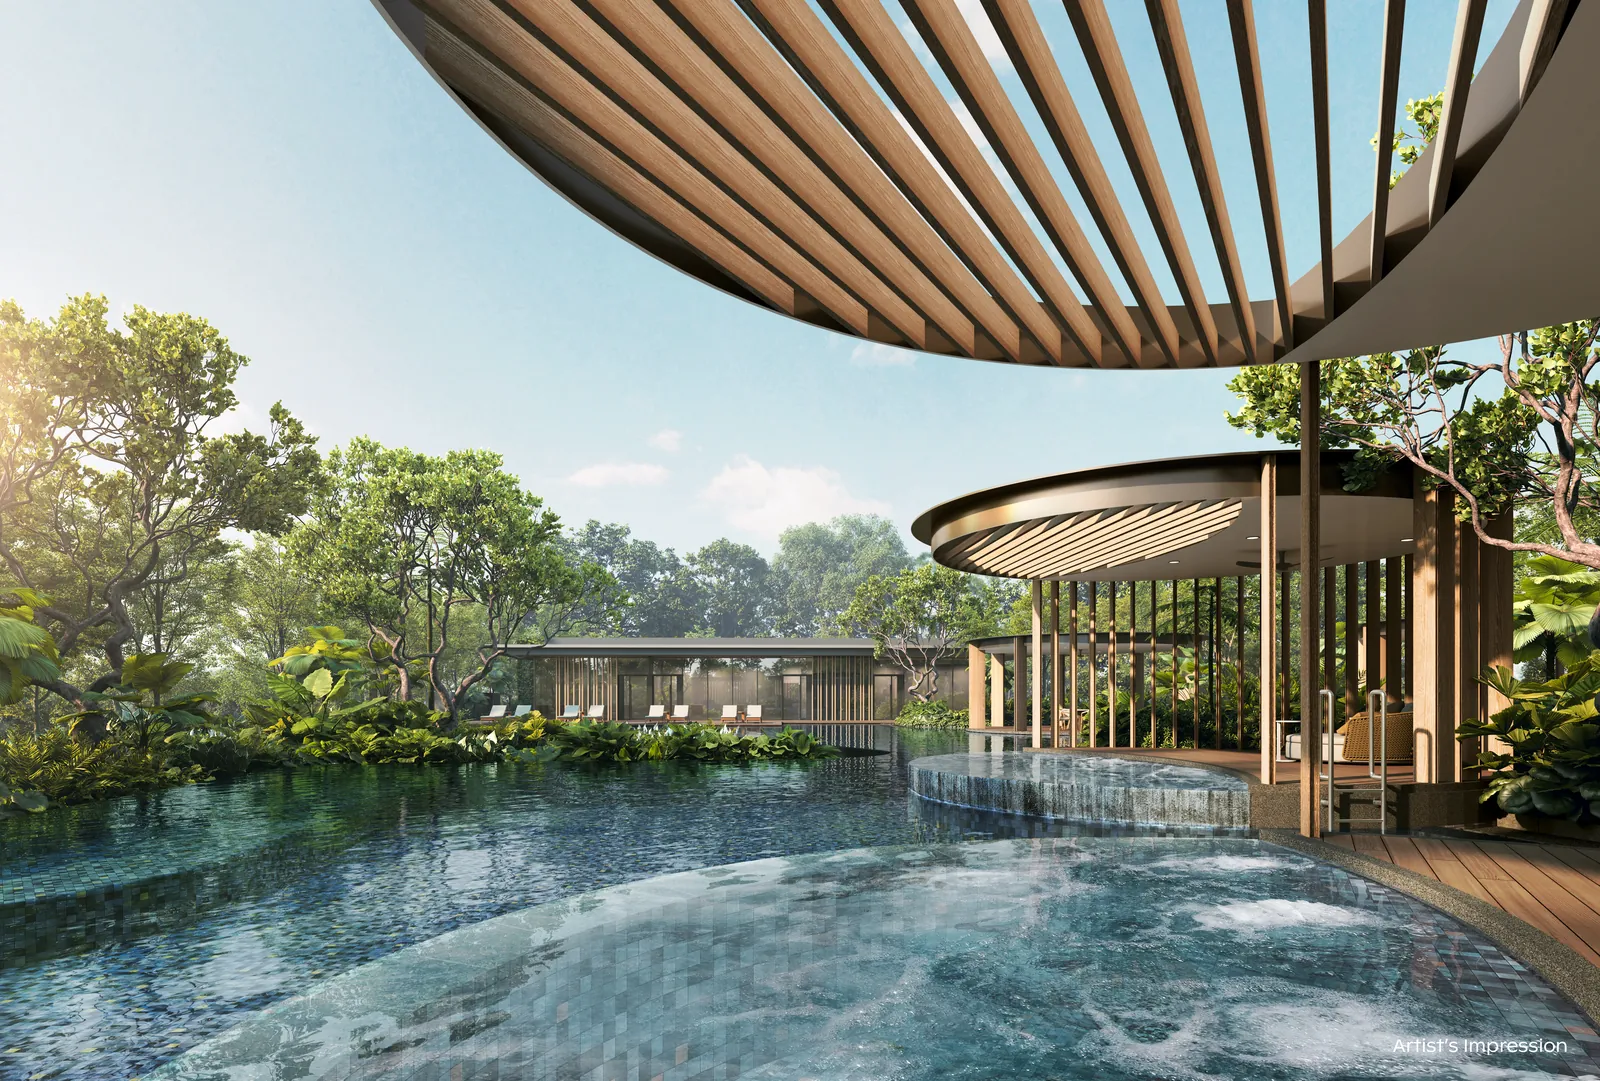
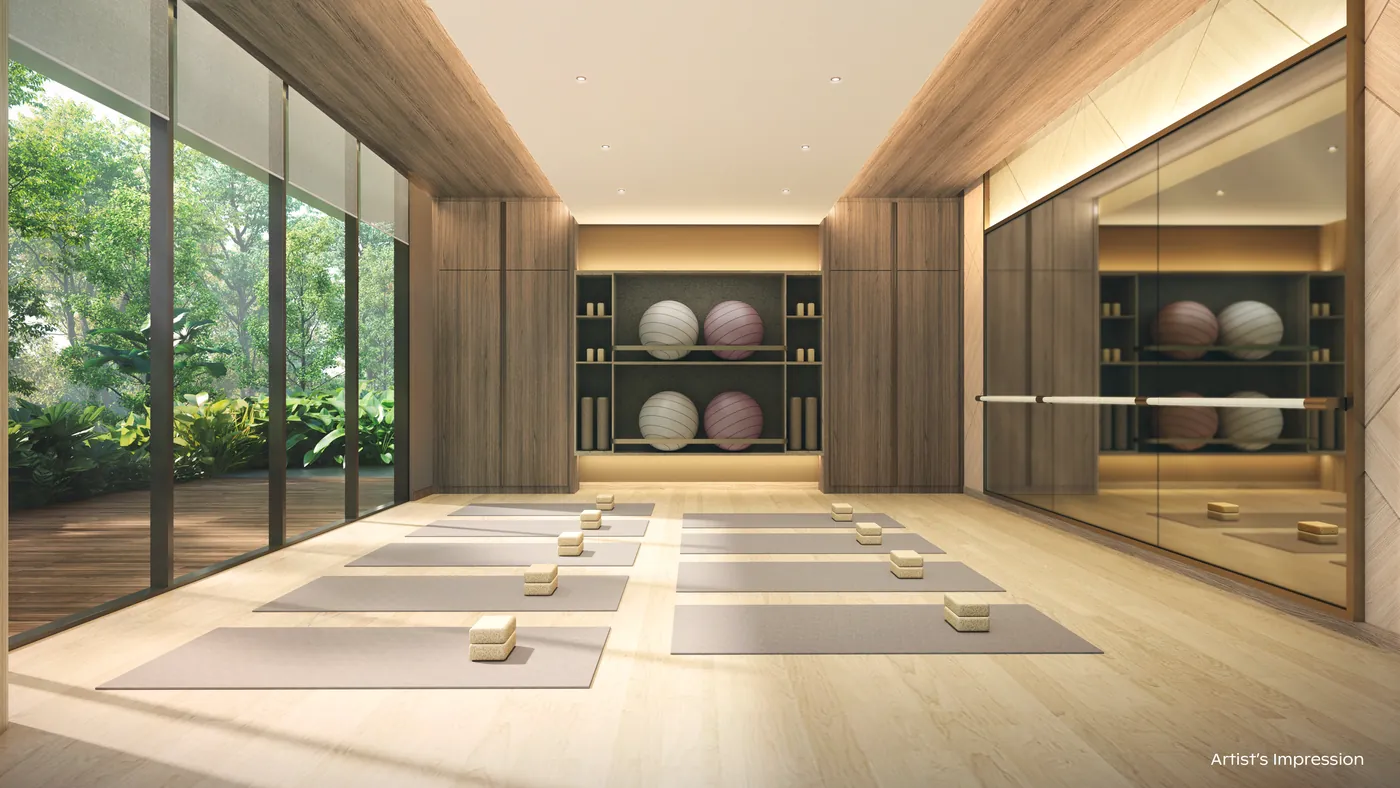
The names below are the developer's, not mine, and every image is its own artist's impression.
Club one of three
Island Club
Resort-style pools and water features set within a landscaped island enclave, together with the arrival court and the first cluster of function and entertainment rooms.
Club two of three
Grand Clubhouse
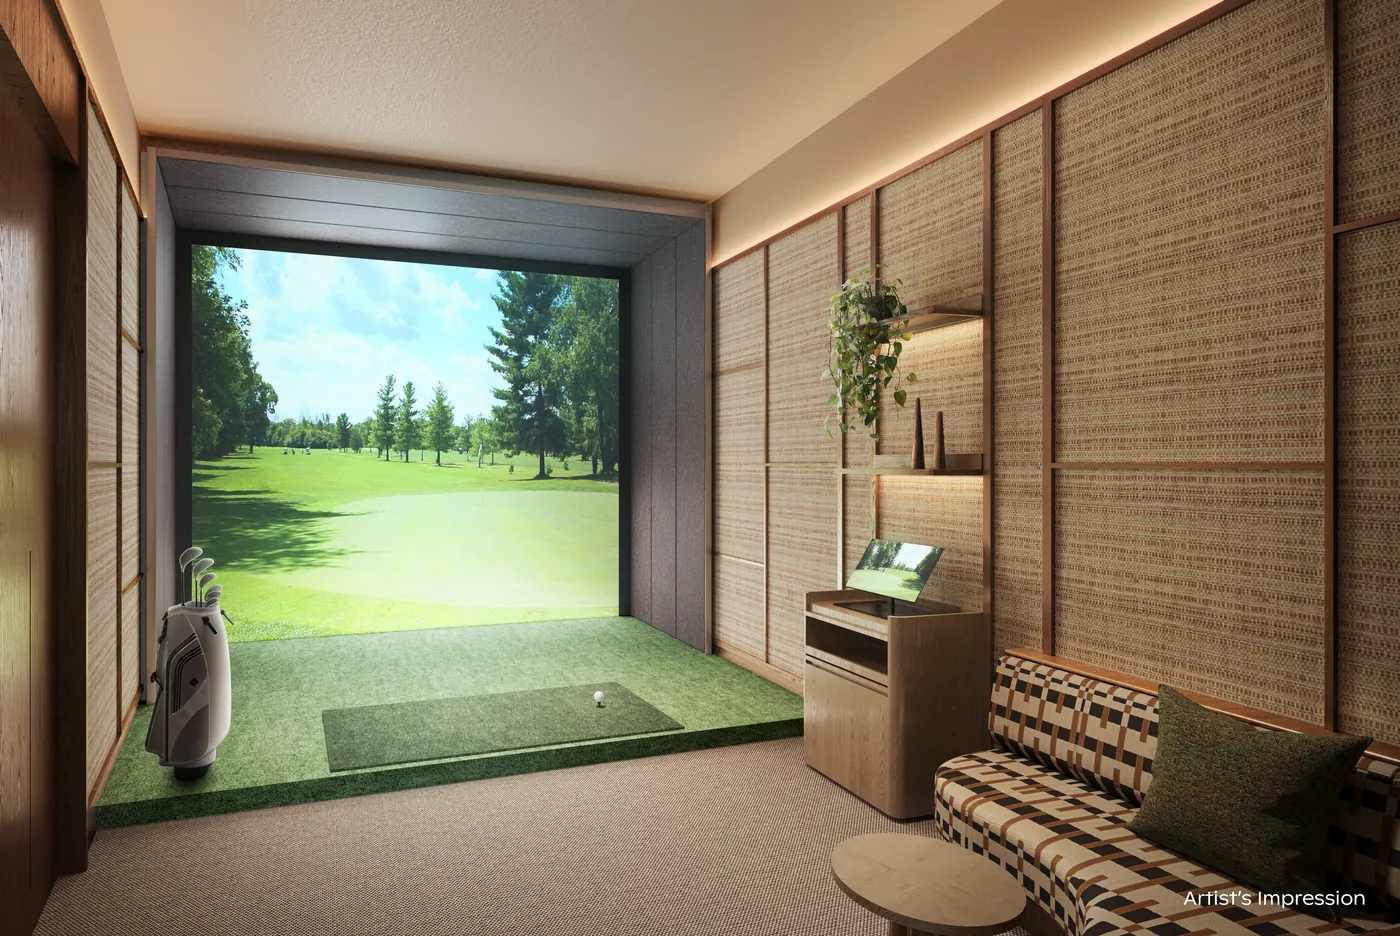
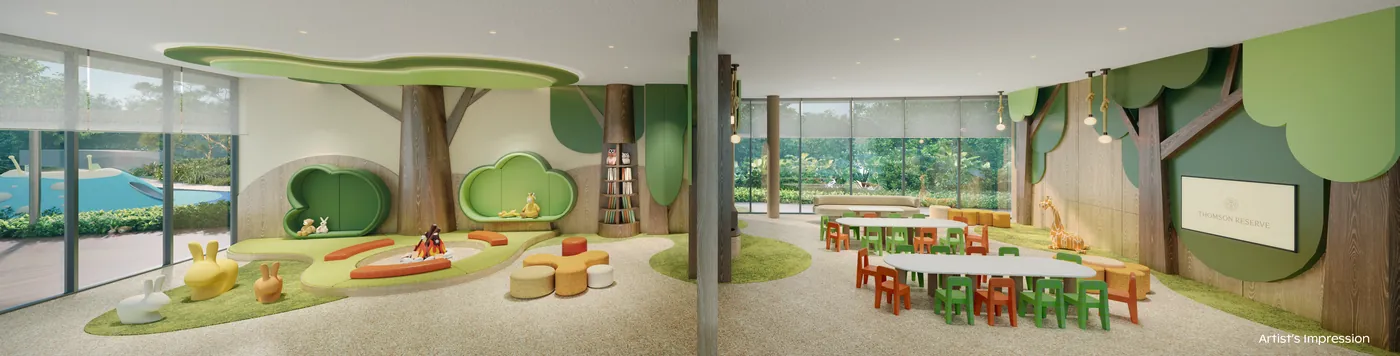
The social heart of the development: function rooms, dining pavilions and lounges for gatherings large and small, plus the main gym, the golf simulator and the two children's rooms.
Club three of three
Wellness Club
A private gym, studio spaces and spa-inspired areas set aside for recovery rather than for socialising.
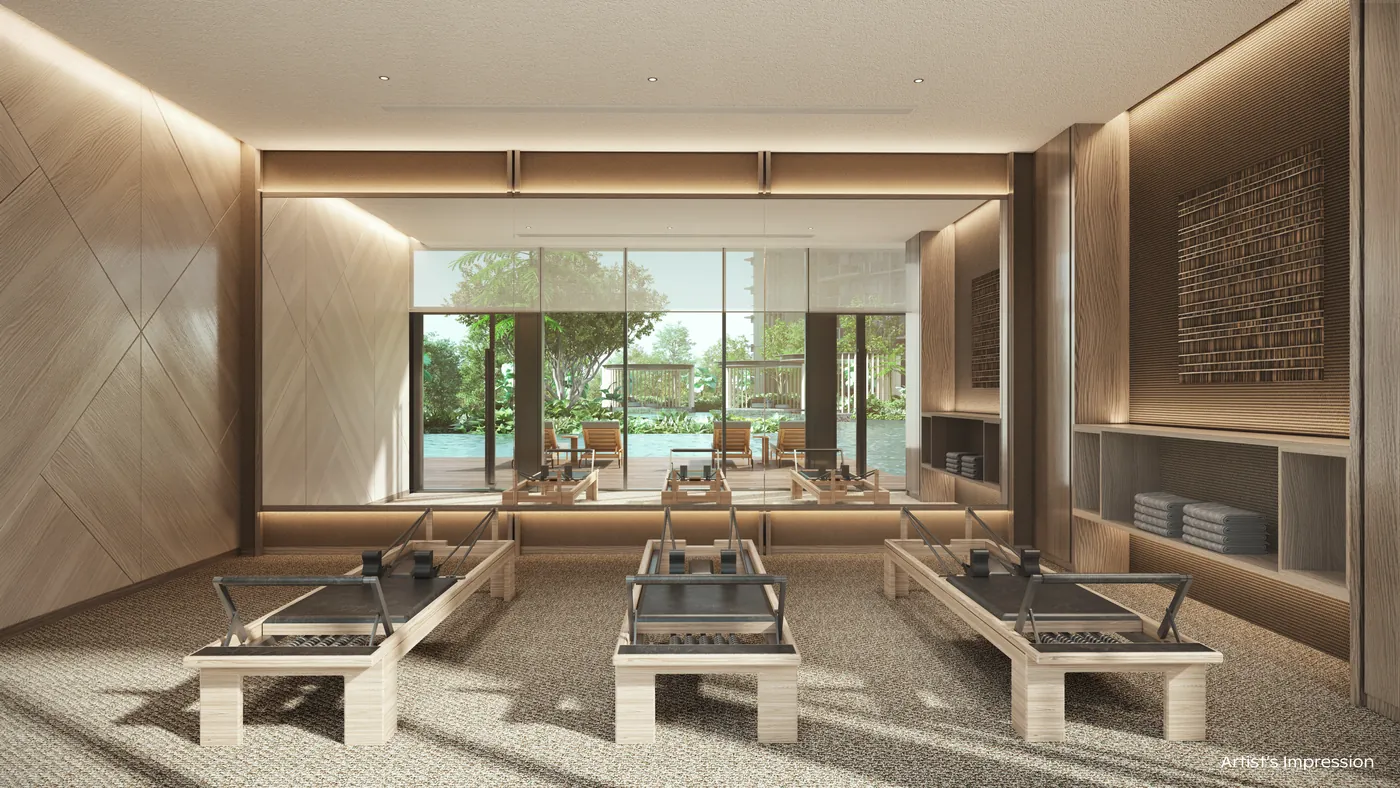
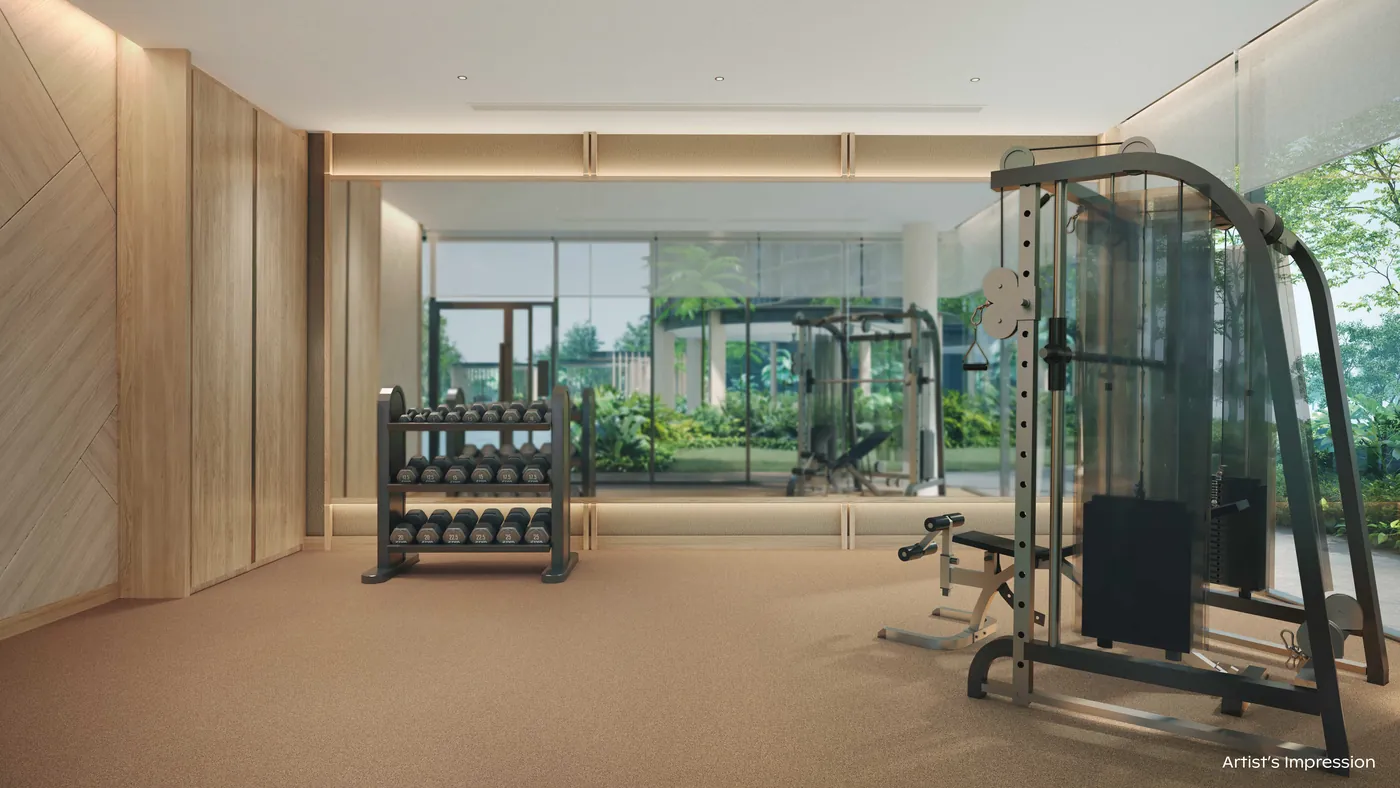
Now, why does any of this matter to a buyer rather than to a brochure?
Because facilities of this depth are normally funded by scale, and scale is the thing people hold against a 1,268-unit project.
Two 50-metre lap pools, a golf simulator, a hydro spa and two separate children's rooms are affordable to build and maintain precisely because there are 1,268 households sharing the bill.
The size everyone worries about is the same fact as the facilities everyone wants.
You do not get one without the other.
One caution, stated once. Facility names, counts and finishes are confirmed only in the sales gallery, and the “more than 80” figure is the developer's own. Verify anything you are buying for.
If you want the images on their own, without any of the commentary on this page, every one the developer has released sits in the Thomson Reserve gallery and teaser film.
9. Who Is Building It?
Three listed developers, jointly.
They build through a joint venture called Tamarind Development Pte Ltd.
CapitaLand Development is the development arm of the CapitaLand Group, with a portfolio the group puts at around $17.8 billion across Singapore, China and Vietnam. Its local record includes The Interlace and Sky Habitat.
UOL Group is a listed property and hospitality group with roughly $22 billion in total assets, and a long District 20 record including The Panorama in Ang Mo Kio. Its recent launches include Pinetree Hill and Parktown Residence.
Singapore Land Group is majority-owned by UOL, so two of the three partners act as one.
That last detail is worth more than it looks.
It cuts the risk of joint-venture partners pulling in different directions on design, pricing or timing.
And here is why any of it matters in practice.
You are paying for a home roughly five years before you can live in it.
Until keys, the builder's balance sheet and record are the main protection you have against delay, defects and disputes.
On that measure this is about as strong a line-up as the Singapore market offers. It does not make any price right. A good builder never rescues a bad entry price, which is why section 3 comes before this one.
10. What Have Homes On This Stretch Actually Returned?
Better than most buyers expect.
This is the section most launch material leaves out, so read it slowly.
Across 3,822 matched buy-and-sell pairs in District 20 from March 1995 to August 2026, the middle seller earned about 4.7% a year.
95.0% of those sales made money.
The middle gain, when it worked, was $411,000 before costs. The middle loss, when it did not, was about $61,000.
The middle holding period was 7.7 years.
For comparison, the whole city-fringe ring managed about 3.8% a year across 45,914 exits, with 90.1% profitable.
So District 20 has beaten its own segment, on a wide base, over a window covering the Asian financial crisis, the global financial crisis and the pandemic.
Now the project-level view, which is the closer read.
| Project | TOP | Exits | Profitable | Median return a year | Median hold | Median gain |
|---|---|---|---|---|---|---|
| Clover by the Park | 2011 | 348 | 100.0% | 6.2% | 7.0y | $620k |
| AMO Residence | 2025 | 41 | 100.0% | 5.5% | 3.7y | $467k |
| Grandeur 8 | 2005 | 626 | 97.4% | 5.5% | 7.3y | $471k |
| The Gardens at Bishan | 2004 | 812 | 97.4% | 5.4% | 9.1y | $433k |
| Jadescape | 2022 | 318 | 100.0% | 5.4% | 4.5y | $371k |
| The Panorama | 2017 | 299 | 100.0% | 4.6% | 7.3y | $380k |
| Goldenhill Park Condominium | 2004 | 268 | 86.6% | 4.5% | 8.8y | $510k |
| Tresalveo | 2012 | 46 | 100.0% | 4.3% | 8.5y | $370k |
| Sky Vue | 2016 | 263 | 99.2% | 3.0% | 7.7y | $245k |
| Thomson View Condominium | 1987 | 95 | 67.4% | 2.9% | 9.2y | $278k |
Eight of those ten projects returned 4.3% a year or better.
Seven of the ten never recorded a losing resale at all.
The middle project of the ten sat at about 5.0% a year.
Look now at the bottom row, because it is the one a sceptic will reach for.
Thomson View Condominium is the worst performer on the table.
2.9% a year, and only 67.4% of its resales made money.
Thomson View is the building that stood on this exact site.
Does that sound damning?
It should not.
Thomson View was completed in 1987 on a lease that started in 1975, so its sellers were trading a lease already thirty and forty years down.
The same location, in newer buildings with more lease left, produced 5.4% at The Gardens at Bishan and 6.2% at Clover by the Park.
The location did not underperform. The lease did.
Thomson Reserve resets that clock to a full 99 years, which is precisely the variable that dragged its predecessor down.
Two honest caveats before you lean on any of this.
A median describes what the middle seller realised. It is never the probability that your purchase does the same.
And an owner sitting on a paper loss can simply decline to sell, so the true loss rate across all purchases is higher than the recorded 5.0%.
The full working behind these figures, run against 32,414 resale exits, sits here.
11. How Does It Compare With Everything Else?
On land, it is not close.
Against Land Bought Since 2024
This is the strongest table on the page, and every figure in it is a completed transaction rather than a forecast.
| Site | Awarded | Land cost (psf ppr) | Versus Thomson Reserve |
|---|---|---|---|
| Thomson Reserve (Bishan, D20) | Nov 2024, en bloc | $1,178 | Baseline |
| Lentor Central (Ang Mo Kio) | 2026 | $1,278 | 8% more |
| Dorset Road (Kallang) | 2025 | $1,338 | 14% more |
| Kallang Close (Kallang) | 2026 | $1,415 | 20% more |
| Tanjong Rhu Road (Kallang) | 2026 | $1,455 | 24% more |
| Dover Drive (Queenstown) | 2026 | $1,556 | 32% more |
| Dunearn Road (Bukit Timah) | 2026 | $1,625 | 38% more |
| Bukit Timah Road (Newton) | 2025 | $1,820 | 55% more |
If you are choosing between Thomson Reserve and the launches that follow it in 2027 and 2028, this table is the whole argument.
They will be built on land costing 8% to 55% more.
That gap has to end up in somebody's price.
Against Homes You Could Buy Today
Here the picture is more finely balanced, and I want you to see it that way.
| Project | District | Completed | 2026 average resale psf |
|---|---|---|---|
| Thomson Reserve | D20 | 2031 (est.) | $2,370 to $2,680 (est. launch) |
| AMO Residence | D20 | 2026 | ~$2,549 |
| Lentor Modern | D26 | 2026 | ~$2,404 |
| Artisan 8 | D20 | Selling now | ~$2,361 |
| Jadescape | D20 | 2022 | ~$2,356 |
| Thomson Three | D20 | 2016 | ~$2,204 |
Read across it and the shape of the trade becomes clear.
At the bottom of my range, a brand-new 99-year lease prices between Jadescape and Lentor Modern.
That is unusual for a new launch, and it is the outcome worth waiting to see.
At the top of the range it sits above everything on the stretch.
Which is why the number that decides this purchase is not the land cost. It is where inside $2,370 to $2,680 the price list actually lands.
If you want the wider trade-off set out properly, I have written it up in new launch versus resale condo, and the rest of this year's pipeline sits in my Singapore project reviews.
12. What Could Go Wrong?
Five things. Here they are.
I would rather you hear these from me now than discover them in a sales gallery.
- The price list lands at the top of the range. At $2,680 psf the land discount has not reached you, and you are paying above everything already standing on the corridor. What cuts it down: you are not obliged to book. Write your ceiling down before preview, and hold to it.
- The entry price may outrun local upgrader budgets. On my range, a 3-bedroom lands at $2.25m to $2.55m. A five-room flat in Bishan or Sin Ming rarely frees up that much once the loan is repaid and CPF is refunded. What cuts it down: the 84% two and three-bedroom mix means smaller layouts stay reachable. The gap still has to be checked on your own numbers, not assumed away.
- 1,268 homes reach completion together. Around 2031 a large block of units hits the rental and resale market at the same time. What cuts it down: no further large site in the immediate area appears in the current confirmed land sales list, and this corridor has absorbed Thomson Three and Thomson Impressions steadily rather than glutting.
- The city-fringe market is soft right now. URA's 2Q2026 data shows non-landed prices in the Rest of Central Region fell 1.2% over the quarter. What cuts it down: softness is exactly when a cheap land cost pays. The developer can price into weakness instead of defending a thin margin.
- The nearest neighbours were only middling over a five-year window. Thomson Impressions and Thomson Three both returned about 2.8% a year on profitable resales held five to seven years, below the District 20 rate. What cuts it down: those owners bought at 2013 to 2019 prices, and the longer-held District 20 record in Table 7 is materially better. It does mean this is a ten-year purchase rather than a five-year trade.
And one more, which is not a risk of the project but a risk of the process.
A launch of this profile is likely to be oversubscribed on the popular stacks.
There is a real chance you do not secure your preferred unit, or any unit, on booking day.
That is an argument for going in with a ranked shortlist, not an argument for going in casually.
13. Who Should Buy, And Who Should Not?
It Fits Well If You Are
An upgrader from Bishan, Sin Ming or Ang Mo Kio. You keep your school, your family nearby and your routine, and reset the lease clock to 99 years. The 84% mix was built for you. Start with the sale rather than the purchase; I have set out the sequence in how to sell your HDB flat.
A family organised around Ai Tong. Inside the 1km band, a nine-minute walk, in a district full of alternatives if the ballot goes against you. Go in knowing the ballot odds in section 7.
An owner of a nearby 2016 to 2022 condo. You may be sitting on a gain worth taking, and a fresh lease is worth more to you than to most. Whether the trade works turns on your numbers, not on the project.
A buyer on a ten-year view. Table 7 is the evidence for this address, and the strongest rows on it were earned over seven to nine years.
An investor treating the land cost as a margin of safety. Not as a yield play. The running yield here will be modest, because you enter above Thomson Three while renting into the same corridor.
It Fits Poorly If You Are
Stretching to the last dollar. If the purchase only works with your flat sale and nothing else, the 3-bedroom is likely out of reach and the 2-bedroom will be tight. That is a real constraint, not one a payment schedule dissolves.
Buying mainly for rental income. Thomson Three rents on the same stretch at a much lower entry price. The case here is the land cost and the 2030 line, not the monthly cheque.
Planning to sell within five years. The record over that window on this stretch is about 2.8% a year before costs, and interest alone eats a large part of it.
If you want the framework I run before recommending any launch, it is in what I look at when advising a buyer on a new launch.
14. What Does It Cost You On The Day?
Five per cent, in cash.
Normal private condominium rules apply. There is no citizenship bar and no minimum occupation period.
Additional Buyer's Stamp Duty. A Singapore Citizen pays nothing on a first home, 20% on a second and 30% on a third. A Permanent Resident pays 5% on a first and 30% on a second. Buyer's Stamp Duty applies on top, on a tiered scale. Confirm current rates at IRAS before you commit.
Borrowing limits. Your total monthly loan repayments are capped at 55% of gross monthly income, tested at an assumed interest rate of 4%. A first housing loan can cover up to 75% of the price.
Seller's Stamp Duty. For options exercised from 4 July 2025, this runs for four years from the date you exercise, not from when you collect keys. On a project completing around 2031, a buyer at an October 2026 preview would normally be clear of it before moving in.
Progressive payments. You pay 5% on booking. Then 15% plus Buyer's Stamp Duty when you exercise the option. Then staged amounts as the building reaches each stage, with the balance at the end.
That spreads the cash over roughly five years.
It is the main reason a home under construction is easier to fund than a resale one, and it is the quiet advantage most buyers underweight.
The one solid step before any preview is an in-principle approval from your bank.
It costs nothing.
It turns “what can I afford” into a number, so you shop for layouts you can actually book.
The rest of the preparation, and what the day itself looks like once queue numbers are out, is in my guide to booking day at a Singapore new launch.
Want this run against your own numbers? I will work out your affordability, stamp duty position and, if you are upgrading, the sale-and-purchase sequence, whichever way you end up deciding. No obligation and no pressure to transact. Book a consultation or message me on WhatsApp.
15. My Take: The Discount Is In The Land, Not In The Price List
I have sat with enough District 20 upgraders to know what usually decides this purchase, and it is rarely a land cost chart.
So let me put the pieces together in the way I would across a table.
Three facts on this page do not depend on a price nobody has published yet.
The land was bought at $1,178 psf ppr and cannot be re-priced.
The station is four minutes away and already running.
The developers are three listed companies, two of them under common control.
None of those three is a forecast. All of them are checkable today.
Now watch what happens when you put them next to each other.
The cheap land is what lets a developer price into a soft quarter without defending a thin margin.
The soft quarter is precisely the market Thomson Reserve is launching into.
And the 84% family mix is what tells you the developer intends to sell volume rather than hold out for a record psf on a handful of penthouses.
Cheap land plus a soft market plus a volume mix is a combination that tends to favour the buyer, and it is not a combination that repeats often.
The launches queuing behind this one sit on land costing 8% to 55% more.
They will find it harder to make the same offer.
Now the part that gets left out when this project is written up.
None of that tells you what the price list will say.
A cheap land cost is permission to price keenly. It is not a promise to.
At $2,400 psf the discount has reached you. At $2,680 it has not, and you are paying above everything already standing on this corridor.
The whole case turns on which of those two happens, and that is a fact nobody has yet.
The second thing worth saying plainly is about time.
This reads as a ten-year home rather than a five-year trade.
The best returns in Table 7 were earned over seven to nine years, and the weakest numbers on this stretch came from short holds and old leases.
If your horizon is three years, no amount of cheap land saves you from stamp duty and interest.
So what I would actually say to someone sitting across the table is not buy or do not buy.
It is that this is a project worth being ready for, on the specific condition that you decide your ceiling before October rather than in the room.
Prepare, then decide.
That order matters more than the decision itself.
16. The Short Version
Eight things to take away
- Thomson Reserve is 1,268 homes at Bright Hill Drive, District 20, on a fresh 99-year lease, by CapitaLand Development, UOL Group and Singapore Land Group. Preview is targeted for October 2026.
- The land cost $1,178 psf ppr, awarded November 2024. Every comparable central-region site awarded since has cost 8% to 55% more.
- The estimated breakeven is $2,058 psf ppr, and my working launch range is $2,370 to $2,680 psf (est.). No developer price exists yet.
- The confirmed unit mix is 84% two and three-bedroom (1,066 homes) and 16% four and five-bedroom (202 homes). It was built for families, not for flippers.
- Three clubs and more than 80 facilities across roughly 5 hectares: Island Club, Grand Clubhouse and Wellness Club, including two 50-metre lap pools.
- Upper Thomson MRT is a four-minute walk today. Bright Hill becomes a Cross Island Line interchange, targeted 2030. Treat the second line as upside.
- Ai Tong School is about 0.57km away, inside the 1km band. In 2025 its Phase 2C ballot had 76 applicants within 1km for 43 places. Inside the band buys a ballot, not a place.
- District 20's long record is strong: 95.0% of 3,822 resales made money, at about 4.7% a year. Eight of the ten tracked projects returned 4.3% a year or better.
So what should you do with this?
Three things, in order, and all of them before October.
- Get an in-principle approval from a bank now. It turns your budget into a number a sales team cannot move.
- If you are selling an HDB flat, work out your bridging position and your timing first. That decision has a longer lead time than the launch does.
- Write down, in advance, the highest psf at which each layout still works for you. Then compare the price list against that number, not against the atmosphere in the room.
Do those three and you will walk into the preview with a plan instead of a hope.
17. Frequently Asked Questions
Should I buy Thomson Reserve?
Nobody can answer that honestly until the price list exists. What can be said in August 2026 is that the land was secured at $1,178 psf ppr in November 2024, cheaper than every comparable central-region site awarded since by 8% to 55%, and that Upper Thomson MRT is a four-minute walk and running today. Those are the strong parts of the case. The condition I would attach is a ten-year holding view and a launch price in the lower half of the estimated $2,370 to $2,680 psf range. At the top of that range the land advantage has not reached the buyer.
When does Thomson Reserve launch?
The showflat preview is targeted for October 2026, with two candidate dates circulating, 3 and 10 October. The developer has confirmed neither. Booking usually follows within a week or two. Floor plans, unit sizes and the price list all land at preview.
How much will Thomson Reserve cost per square foot?
No price list exists yet. My working estimate is $2,370 to $2,680 psf. It is built from an estimated breakeven of $2,058 psf ppr times a developer margin band of 15% to 30%. A second method uses the middle land-to-launch multiple of 2.12 across 53 launched projects, which gives about $2,500 psf and sits inside the range. Both are estimates, not quotes.
What would a 3-bedroom at Thomson Reserve cost?
On the estimated range of $2,370 to $2,680 psf, a 950 sq ft 3-bedroom would land at roughly $2.25 million to $2.55 million. A 700 sq ft 2-bedroom would be about $1.66 million to $1.88 million, and a 1,150 sq ft 4-bedroom about $2.73 million to $3.08 million. These apply an estimated price to typical sizes. The developer has published neither prices nor unit sizes.
What is the unit mix at Thomson Reserve?
The developer has confirmed a two-band split across ten layouts. The 2-Bedroom, 2-Bedroom Premium, 2-Bedroom Premium + Study, 3-Bedroom, 3-Bedroom Premium and 3-Bedroom Premium + Study types together account for 1,066 homes, or 84%. The 4-Bedroom, 4-Bedroom Premium, 4-Bedroom Premium + Study and 5-Bedroom Suite types account for 202 homes, or 16%, with three of those four large layouts served by a private lift. Individual counts and sizes for each layout are released at preview.
What facilities does Thomson Reserve have?
The developer describes more than 80 facilities across roughly 5 hectares, grouped into three named clubs. The Island Club holds the Grand Arrival, the 50-metre Infinity Lap Pool, the Cedar Room and Entertainment Room 1. The Grand Clubhouse holds the Leisure Pool, the 50-metre Canopy Lap Pool and Hammock Cove, the Grand Lawn Pavilion, the Grand Function Room, the Olive Lounge, the Maple Room, the Main Gym, the Recreation Room, the Golf Simulator and two children's rooms. The Wellness Club holds the Hydro Spa Pool and Wellness Pods, the Wellness Studio, the Pilates Studio and a Private Gym.
Why does the land cost of $1,178 psf ppr matter?
Land is the biggest single cost in any new launch, and it is fixed years before the showflat opens. Thomson Reserve's site was secured in November 2024, before land prices re-rated. Every comparable central-region site bought since has cost between $1,278 and $1,820 psf ppr, or 8% to 55% more. A lower land cost lowers the floor under the launch price and gives the developer room to price competitively. It does not oblige them to.
Is Thomson Reserve within 1km of Ai Tong School?
Yes, on a straight-line measurement of about 0.57km from map coordinates, so it falls inside the 1km band. The Ministry of Education measures home-to-school distance on its own basis, so confirm your block using MOE SchoolFinder. Being inside 1km earns a place in the ballot, not a place at the school. In the 2025 Primary 1 exercise, Ai Tong's Phase 2C ballot had 76 applicants within 1km for 43 vacancies.
Which MRT stations are near Thomson Reserve?
Upper Thomson (TE8) on the Thomson-East Coast Line is about 0.27km away, roughly a four-minute walk, and has been running since August 2021. Bright Hill (TE7) is about 0.82km, roughly twelve minutes. Its Cross Island Line platforms are under construction, with the first stage targeted for 2030, which will make it an interchange between the two lines. Marymount (CC16) on the Circle Line is about 1.28km away.
How many towers does Thomson Reserve have?
Six towers on a site of roughly 5 hectares. Two are 30 storeys, positioned as the signature towers with the longer outlook, and four are 21 storeys. The developer describes the 21-storey towers as holding the largest share of the 1,268 homes. Around 1,014 carpark lots were reported in July 2026, a figure the developer has not published directly.
Who is the developer of Thomson Reserve?
A joint venture called Tamarind Development Pte Ltd, formed by CapitaLand Development, UOL Group and Singapore Land Group. UOL owns most of Singapore Land Group, so two of the three partners are in effect one. CapitaLand Development puts its portfolio at around $17.8 billion across Singapore, China and Vietnam, and UOL reports roughly $22 billion in total assets. UOL's recent projects include Pinetree Hill and Parktown Residence.
Is Thomson Reserve a good investment?
On a seven to ten-year view I think the case is strong, and on a three to five-year view I do not. District 20's long record is good: 95.0% of 3,822 matched resales made money at a middle rate of about 4.7% a year, and eight of the ten tracked projects in the district returned 4.3% a year or better. Against that, the two condominiums nearest this site returned about 2.8% a year on profitable sales held five to seven years. Buy it as a home to hold, not as a trade.
What was on the site before Thomson Reserve?
Thomson View Condominium, a 255-home development completed in 1987 on a lease that began in 1975. Its owners sold the site collectively for $810 million, on the fifth attempt in roughly 17 years, after the asking price was cut from $918 million. The High Court cleared the sale on 1 July 2025. Thomson View's own resale record was the weakest in District 20, at about 2.9% a year, which is largely a story about lease decay rather than about the location.
When will Thomson Reserve be completed?
Around 2031, roughly five years after launch. You pay in stages as the building goes up, so a delay stretches the schedule rather than raising what you owe. Even so, plan your housing with some slack either side of that date.
What if I need to sell within five years?
Seller's Stamp Duty runs for four years from the date you exercise the option, not from completion. For a purchase at an October 2026 preview, that four-year period would normally end before the keys are collected. Check current rates with IRAS before you commit. Note too that a sale before the building is finished is a sub-sale, and that is a much thinner market.
Is Thomson Reserve suitable for an HDB upgrader?
Often yes, and the 84% two and three-bedroom mix is aimed squarely at Bishan, Sin Ming and Ang Mo Kio upgraders. The catch is the bridge. On my estimated range a 3-bedroom costs $2.25 million to $2.55 million, and a five-room flat in the area rarely frees up that much once the loan is repaid and CPF is refunded. Work out that gap before preview, not at booking, and plan the sale before the purchase.
18. Sources And Update Log
Developer material. The unit mix, the tower configuration, the three club names and every facility name and image on this page come from the developer's own presentation materials and factsheet, dated July and August 2026. Images are artist's impressions supplied by the developer. The teaser film is published by the developer on YouTube. Developer marketing claims, including the "more than 80 facilities" figure, are attributed rather than independently verified.
Government sources. Quarterly price movements are from the Urban Redevelopment Authority's 2nd Quarter 2026 real estate statistics, released 24 July 2026. School distances should be verified against MOE SchoolFinder, and locations against OneMap. Stamp duty rates are published by IRAS.
Project, land and sales data. Land cost, cost stack, distances, school bands and resale returns come from PropertyInsider.sg, the research site I publish. It compiles URA caveat and tender data and states its methods. The tracked record for this project is at Thomson Reserve prices, sales progress and district analysis, last refreshed 15 August 2026. The resale return figures come from is Thomson Reserve a good investment, tested against 32,414 exits.
Collective sale details. The $810 million price, the $918 million ask, the $1,178 psf ppr working and the 255-home site history follow the marketing agent's November 2024 notice and news reports at the time. The 1 July 2025 High Court order follows the same reports.
What is still missing. The developer has not published unit sizes, floor plans, stack numbers, a per-layout unit count or any price. Carpark numbers reported in July 2026 are unconfirmed. All of it lands at preview.
Update Log
- 16 September 2026. Added the Lorong Puntong/Sin Ming Avenue tender result at $1,612 psf ppr for land-cost context.
- 27 August 2026. Full rewrite to a journal-style commentary. Replaced every image with the developer's released perspectives, converted to WebP. Added the confirmed 84/16 unit mix, the three-club facility gallery using the developer's own naming, and the official teaser film. Replaced the narrow five-to-seven-year resale table with the full District 20 project leaderboard, and added the Thomson View lease-decay reading. Added the site's 5-hectare and 80-plus facility figures from the developer's presentation. Published a separate image-only gallery page and linked to it.
- 25 August 2026. Corrected the land timeline to the November 2024 award and the 1 July 2025 High Court order. Published the cost stack behind the $2,370 to $2,680 range. Added the Bright Hill Cross Island Line interchange and the 2025 Ai Tong ballot figures.
- 10 June 2026. First published.
- Next update. The day the developer publishes a price list, when every estimate on this page is replaced with confirmed figures and per-layout unit sizes are added.
Disclaimer: This article is general information, not financial, investment, legal or tax advice, and it does not take account of your circumstances. It expresses the author's opinions, which you should weigh against your own research and independent advice. Anything marked (est.) is an estimate and is not developer-confirmed. Images are artist's impressions supplied by the developer; actual finishes, layouts, facilities and views will differ. Resale return figures are gross and exclude stamp duties, mortgage interest, agent commission, legal fees and upkeep, and a median describes past sellers rather than the likely outcome of any purchase. Launch dates, unit counts, layouts and pricing may change. Verify all figures against URA, MOE and IRAS publications, and seek professional advice, before making any decision. Jamus Lee is a licensed property agent (CEA Reg. No. R065771E) with ERA Realty Network Pte Ltd (Licence No. L3002382K) and also publishes PropertyInsider.sg, cited above.